Who Pays for Physical Therapy After Retirement Surgery? Medicare Guide
Find out who pays for physical therapy after retirement surgery under Medicare and how to avoid surprise bills. Call (833)-864-8213 for plan help.
By Kenneth Farrow
Compare health plans
Finding plans in your area…
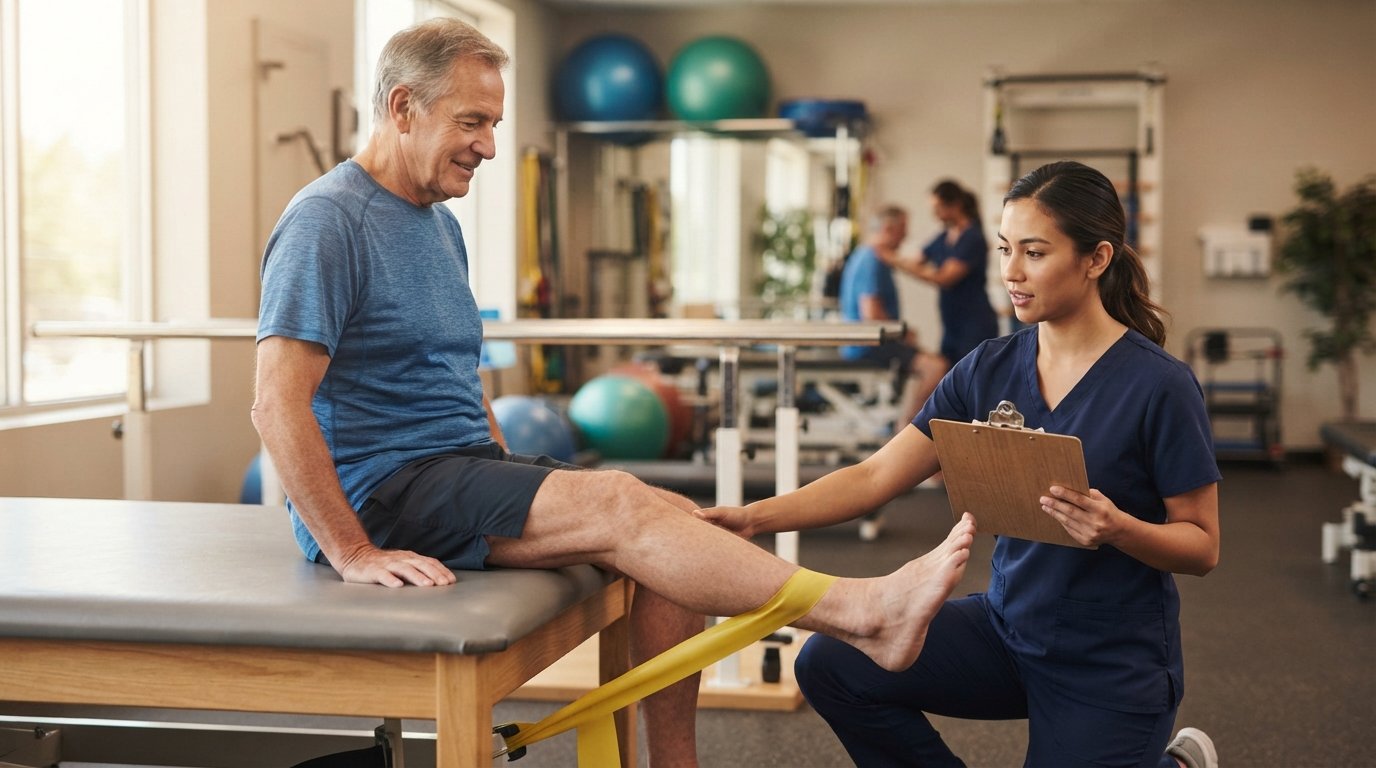
You had the surgery while still on your employer's health plan, and now retirement has arrived with a stack of physical therapy appointments still ahead of you. The bills are starting to arrive, and one question keeps nagging at you: who actually pays for physical therapy after retirement surgery once Medicare becomes your primary coverage? The answer depends on several moving parts, including the type of Medicare plan you choose, whether you kept any retiree coverage, and the exact date your Medicare benefits began. Understanding how these pieces fit together can mean the difference between a smooth recovery and a financial headache during an already stressful time.
How Medicare Covers Outpatient Physical Therapy
Original Medicare, which consists of Part A (hospital insurance) and Part B (medical insurance), treats outpatient physical therapy as a covered service under Part B. That means Medicare will pay its share of the cost for therapy your doctor orders to treat a condition or to help you recover from surgery, as long as you receive care from a Medicare-enrolled provider. The therapy must be considered medically necessary, and your provider must document that your condition is improving or that the therapy maintains your function.
Part B generally pays 80 percent of the Medicare-approved amount for covered physical therapy services after you meet your annual deductible. You are responsible for the remaining 20 percent, known as coinsurance, with no cap on that out-of-pocket amount. For a lengthy course of post-surgical rehab, that 20 percent can add up quickly, which is why so many retirees look for ways to reduce their exposure. If you want a broader walkthrough of how to line up coverage before you retire, the guide on retirement Medicare planning before 65 explains the steps in plain language.
There is some good news on the cost side. Medicare removed the annual therapy cap for outpatient physical therapy years ago, so there is no hard dollar limit on how much therapy Medicare will cover in a year. Instead, Medicare applies a soft threshold, and once your therapy costs exceed a certain amount, your provider must confirm that the care is still medically necessary. You may also owe coinsurance for each therapy session, so it helps to ask your therapist's billing office what your estimated responsibility will be per visit.
Coordination of Benefits When You Retire Mid-Treatment
One of the trickiest situations involves therapy that starts before your retirement date and continues afterward. While you are still working and covered by an employer plan, that plan usually pays first, and Medicare may pay second if you are already enrolled. Once you retire and lose that employer coverage, Medicare typically becomes your primary payer. The transition can create gaps if the handoff is not handled carefully, especially if your employer plan ends on a different date than your Medicare enrollment becomes effective.
To protect yourself, take these steps as soon as you know your retirement date:
- Confirm the exact last day of your employer coverage and request a letter from your HR department documenting it.
- Verify your Medicare Part B effective date so you know when it becomes your primary coverage.
- Tell your physical therapist and their billing office about the change so claims are submitted to the correct insurer.
- Ask whether the therapist is in-network for your new Medicare plan, since provider networks can differ.
If your employer coverage continues through COBRA after you retire, be aware that COBRA is generally not considered primary to Medicare for someone who is eligible for Medicare based on age. That means Medicare may pay first and COBRA second, which can change how your therapy claims are processed. Reviewing your coordination of benefits rules with both insurers before your first post-retirement appointment can prevent denied claims and surprise bills.
How Medigap and Medicare Advantage Reduce Therapy Costs
The 20 percent coinsurance under Original Medicare has no ceiling, and a series of therapy visits can push that number into the hundreds or even thousands of dollars. Medigap plans, also called Medicare Supplement plans, are designed to fill that gap. Plan G, for example, covers the Part B coinsurance after you pay the Part B deductible, which means your out-of-pocket cost for covered physical therapy could drop to zero once the deductible is met. Plan N covers most of the coinsurance but may require a small copay for some office visits, so it is worth checking the details for therapy services.
Medicare Advantage plans take a different approach. Instead of paying coinsurance, you typically pay a copay for each therapy visit, and that copay can vary widely between plans. Some Advantage plans charge a modest flat copay per session, while others use a coinsurance percentage. The trade-off is that Advantage plans often include extra benefits such as dental, vision, and fitness programs, but they also use provider networks, so you need to confirm your therapist participates. Whether Medigap or Medicare Advantage saves you more on therapy depends on how many visits you expect and what you can afford in premiums.
Comparing plans side by side is the surest way to estimate your post-retirement therapy costs. A complimentary plan comparison can show you the premium, copays, and network details for the plans available in your ZIP code, so you can see which option keeps your therapy costs predictable. It also helps to think beyond therapy: if you are also planning for long-term family protection, services like LifeAgency can help you compare life insurance quotes so your broader retirement budget stays balanced.
Timing Issues When Treatment Spans Your Retirement Transition
Timing is where many retirees get caught off guard. If you retire during the middle of a therapy course, you may have claims split between two insurers, and each may request documentation from the other. A claim submitted to the wrong plan first can be denied and must be resubmitted, which delays payment and sometimes results in a temporary bill to you. Keeping a simple log of visit dates, the insurer billed, and the amount paid can help you spot problems early.
Another timing issue involves the Medicare enrollment window. If you are retiring after age 65 and had employer coverage through your own or a spouse's active employment, you may qualify for a Special Enrollment Period to sign up for Part B without a late penalty. The key is to enroll promptly once employment ends. If you delay, you could face a gap in coverage right when your therapy bills are arriving. Checking your enrollment options before your last day of work gives you time to choose a Medigap or Advantage plan that fits your rehab needs.
It also helps to ask your surgeon and therapist for a written care plan that estimates how many visits you will need. With that number in hand, you can run a rough calculation: multiply the visits by your expected copay or coinsurance under each plan you are considering. That simple exercise often reveals which plan type is the better financial fit for your recovery period.
What to Do If a Therapy Claim Is Denied
Denials happen, and they are not always final. If Medicare or your plan denies a physical therapy claim, review the explanation of benefits to understand the reason. Common reasons include missing documentation, a provider who is not enrolled in Medicare, or a determination that the therapy was not medically necessary. You have the right to appeal, and many denials are overturned when the proper records are supplied.
Start by contacting your therapist's office and asking them to submit additional documentation, such as progress notes and the plan of care. Then follow the appeal instructions on your Medicare Summary Notice or plan denial letter. Keep copies of everything you send, and note the deadlines, which are typically strict. If you are on a Medicare Advantage plan, the appeal process runs through the plan rather than Original Medicare, so check your plan's member handbook for the specific steps.
For ongoing therapy, it also pays to confirm that your provider accepts Medicare assignment. If a therapist does not accept assignment, they can charge you more than the Medicare-approved amount, which increases your share. Asking this question before your first visit avoids unpleasant surprises later.
Planning Ahead to Keep Therapy Affordable
The most reliable way to control physical therapy costs after retirement surgery is to choose coverage with your rehab needs in mind. If you expect an extended course of therapy, a Medigap plan that covers the Part B coinsurance can turn unpredictable 20 percent charges into a predictable premium. If you prefer lower premiums and are comfortable with copays and network rules, a Medicare Advantage plan may work well, provided your therapist is in the network.
Take a few practical steps before your first post-retirement appointment:
- Confirm your Medicare effective date and whether Part B is active.
- Ask your therapist which insurance plans they accept and whether they participate in Medicare.
- Estimate your per-visit cost under each plan you are considering.
- Keep a folder with claim records, explanations of benefits, and appeal deadlines.
With those details in hand, you can move through recovery knowing exactly who is paying for what, and you can adjust your plan choice during the next enrollment opportunity if your needs change. A little preparation now keeps the focus where it belongs: on getting stronger.
Compare health plans
Finding plans in your area…