Senior Assistance Programs for Healthcare and Living Costs
Senior assistance programs can lower healthcare and living costs. Call (833)-864-8213 to review Medicare plan options with a licensed agent.
By Vanessa Caldwell
Compare health plans
Finding plans in your area…
For millions of older adults, the gap between what Medicare covers and what daily life actually costs can feel impossible to close. A hospital stay may leave behind a coinsurance bill. Prescription copays can eat into a grocery budget. Utility bills climb in extreme heat or cold, and rent or property taxes demand a growing share of a fixed income. The good news is that a wide network of senior assistance programs exists to help pay for healthcare and living costs, and many eligible households never apply because they simply do not know these programs exist. This guide walks through the major categories of aid, explains who tends to qualify, and shows how to find local help. It is educational only, not financial or legal advice, and program rules can change, so always confirm details with the sponsoring agency.
Medicare Savings Programs: Help With Premiums and Cost Sharing
Medicare Savings Programs (MSPs) are state-administered programs that help people with limited income and resources pay some or all of their Medicare costs. There are four main levels. The Qualified Medicare Beneficiary (QMB) program pays the Part B premium and, in most cases, eliminates cost sharing for Medicare-covered services. The Specified Low-Income Medicare Beneficiary (SLMB) program pays the Part B premium. The Qualifying Individual (QI) program also pays the Part B premium but is funded on a first-come, first-served basis each year. The Qualified Disabled and Working Individuals (QDWI) program helps certain working people with disabilities pay the Part A premium.
These programs are a first stop because they can free up hundreds of dollars per month. A person who qualifies for QMB, for example, may no longer face 20 percent coinsurance on doctor visits and hospital care, which can be the difference between affording care and skipping it. Because MSPs are run by state Medicaid agencies, income limits and application processes vary. In most states, the asset test is modest, and some states have eliminated it entirely. If you are unsure where to begin, our guide to Medicare Savings Programs for low-income individuals explains the eligibility tiers in more detail.
Medicaid and Dual Eligibility for Seniors
Medicaid is the joint federal-state program that provides health coverage to people with very low income and limited resources. For seniors, Medicaid often works alongside Medicare. People enrolled in both are called dual eligibles, and they may receive full Medicaid benefits, help with Medicare premiums, and long-term services and supports such as nursing home care or home and community-based services. Medicaid can also cover dental, vision, and hearing services that Original Medicare typically excludes.
Eligibility rules differ dramatically from state to state. Some states have expanded Medicaid under the Affordable Care Act, while others have not, and income counting rules for seniors can include complex deductions for medical expenses. A benefits counselor can help you understand whether you qualify and how to apply. It is also worth noting that Medicaid estate recovery rules may apply to certain benefits received after age 55, so families should ask questions before signing up for long-term care services.
Food, Energy, and Daily Living Assistance
Healthcare is only part of the cost puzzle. Housing, food, and utilities consume a large share of most senior budgets, and several federal programs target these needs directly. The Supplemental Nutrition Assistance Program (SNAP) provides monthly benefits for groceries, and older adults may qualify even with somewhat higher incomes because medical expense deductions are allowed. The Low Income Home Energy Assistance Program (LIHEAP) helps with heating and cooling bills and, in some cases, weatherization and emergency repairs. The Supplemental Security Income (SSI) program provides cash assistance to people with limited income and resources who are aged, blind, or disabled.
Other programs worth exploring include Section 202 Supportive Housing for the Elderly, which subsidizes rental housing, and the Property Tax Relief programs offered by many states and localities. Some utility companies also offer discounted rates for low-income seniors. The key is to apply through the right agency: SNAP through the state social services department, LIHEAP through the state energy office or a local community action agency, and property tax relief through the county assessor or treasurer. A single application through a benefits screening tool can often reveal several programs at once.
State Pharmaceutical Assistance Programs
Even with Medicare Part D, prescription drug costs can be daunting, especially for specialty medications or during the coverage gap. More than 20 states operate State Pharmaceutical Assistance Programs (SPAPs) that help residents pay premiums, deductibles, or copays for prescription drugs. Some programs are limited to specific conditions, such as HIV or cancer, while others are broader. Eligibility usually depends on income, age, and residency, and benefits vary widely.
In addition to state programs, manufacturer patient assistance programs and nonprofit copay foundations can help with expensive drugs. The Medicare Part D Extra Help program, also called the Low-Income Subsidy, is a federal benefit that reduces Part D premiums and copays for people with limited income and resources. Applying for Extra Help is free, and approval can meaningfully lower monthly drug costs. Because formularies and program rules change each year, it is smart to review your drug list with a licensed agent during the Annual Enrollment Period.
How to Find Area Agencies on Aging and Benefits Counselors
One of the most reliable ways to find local help is through the national network of Area Agencies on Aging (AAAs). These organizations are designated by the Older Americans Act to serve adults age 60 and older, and they connect people to meals, transportation, caregiver support, insurance counseling, and benefits enrollment assistance. Every state has a State Unit on Aging that can point you to the AAA covering your ZIP code. The Eldercare Locator, a public service of the Administration for Community Living, can also match you with local resources by phone or online.
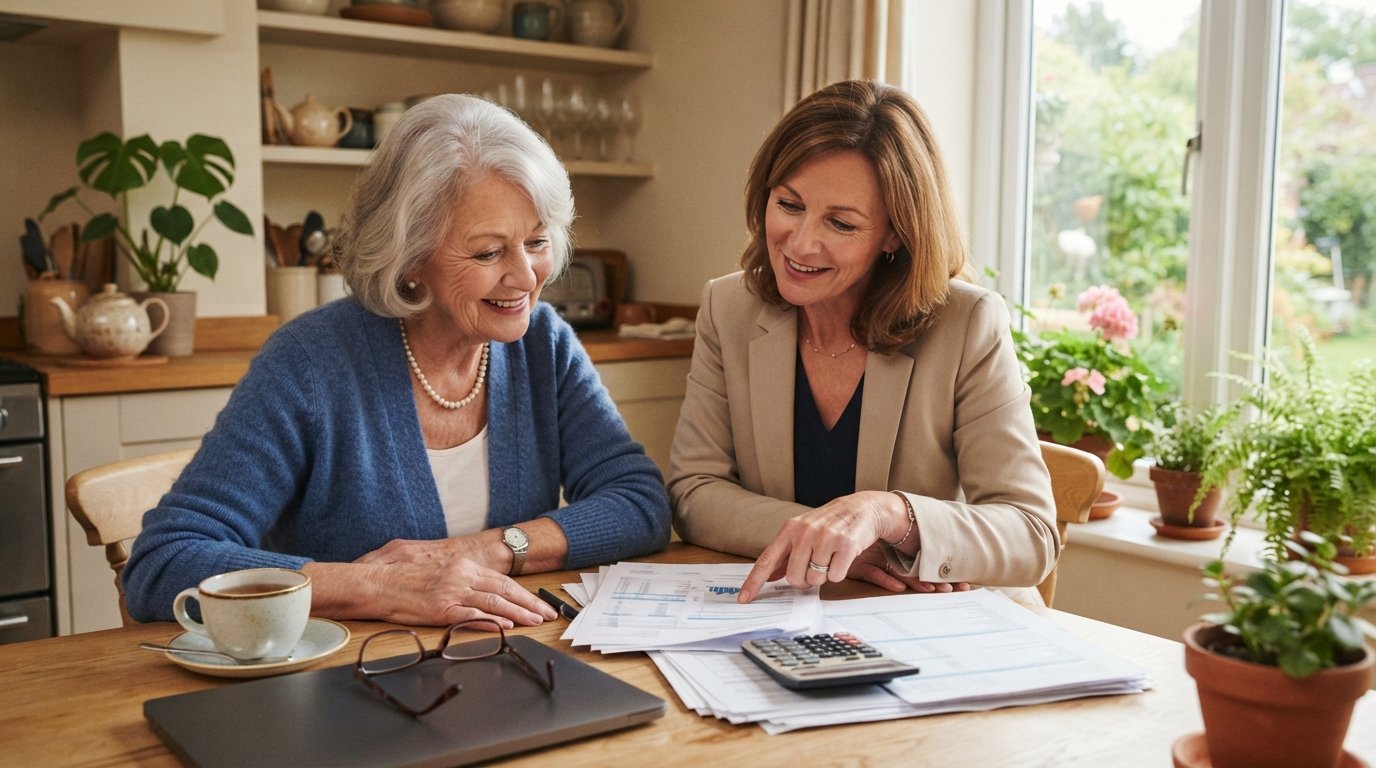
Benefits counselors, often called SHIP counselors (State Health Insurance Assistance Programs), provide free, unbiased help with Medicare questions, including Medicare Savings Programs and Extra Help applications. They do not sell insurance and are not affiliated with any carrier, which makes them a trustworthy starting point. To make the most of an appointment, gather your income documents, recent medical bills, a list of prescriptions, and your Medicare card. A counselor can then screen you for multiple programs in one session and help you complete applications.
Understanding Eligibility: Income, Assets, and Residency
Most senior assistance programs that help pay for healthcare and living costs use three core tests: income, assets, and residency. Income limits are often tied to the Federal Poverty Level (FPL) and may be expressed as a percentage, such as 135 percent of FPL for QMB in many states. Asset limits count savings, investments, and sometimes a home or vehicle, though primary residences are often excluded or counted at a reduced value. Residency requirements usually mean you must live in the state or county where you apply, and some programs require U.S. citizenship or qualified immigrant status.
It helps to know that not all income counts the same. Social Security benefits may be counted differently than wages, and some programs allow deductions for medical expenses, which can bring a household under the limit. Because rules are complex and vary by program, a benefits counselor or the sponsoring agency is the best source of guidance. Never assume you earn too much to qualify; many older adults are surprised to learn they are eligible for at least one program.
NewMedicare.com and Your Coverage Choices
NewMedicare.com is a privately operated educational resource, not a government agency, and it does not provide financial, legal, or medical advice. What it does offer is clear information about Medicare Parts A, B, C, D, and Medigap, along with tools to compare plans and connect with licensed insurance agents. For people who do not qualify for assistance programs, choosing a lower-cost Medicare Advantage or Medigap plan can still reduce out-of-pocket spending. A licensed agent can review your doctors, prescriptions, and budget to find a plan that fits.
It is also wise to plan for the costs Medicare does not cover. Life insurance can help protect a spouse or family from unexpected expenses, and platforms such as USLifeQuote connect consumers with licensed agents who provide personalized quotes. Combining the right health coverage with a realistic financial plan gives seniors more control over both healthcare and living costs.
Practical Steps to Get Started
Applying for assistance can feel overwhelming, but breaking it into small steps makes it manageable. Start by gathering documents, then screen for programs, then apply through the correct agency. The sequence below is a simple framework that works for most households.
- Collect your Social Security card, Medicare card, photo ID, proof of income, bank statements, and a list of prescriptions.
- Contact your local SHIP counselor or Area Agency on Aging for a free benefits screening.
- Apply for Medicare Savings Programs and Extra Help through your state Medicaid agency or Social Security Administration.
- Check SNAP, LIHEAP, and property tax relief through your state or county social services office.
- Review your Medicare plan annually with a licensed agent to keep premiums and copays as low as possible.
Following these steps in order prevents duplication and ensures that each application builds on the last. It also creates a paper trail that can help if an application is delayed or denied. Keep copies of everything you submit and note the date of each application.
Senior assistance programs that help pay for healthcare and living costs are not charity; they are public benefits funded by taxpayers and designed to keep older adults healthy, housed, and independent. Millions of eligible people leave money on the table every year simply because they do not ask. Whether you need help with a Part B premium, a winter heating bill, or a costly prescription, there is likely a program within reach. Take the first step today by calling a benefits counselor or speaking with a licensed agent about your Medicare options, and let the system work for you.
Compare health plans
Finding plans in your area…