Medicare Foreign Travel Emergency Coverage With Medigap
Medigap foreign travel emergency coverage pays 80 percent of emergency care abroad after a $250 deductible, up to a $50,000 lifetime maximum. Learn which plans include it and how to prepare before you travel.
By Raymond Tolliver
Compare health plans
Finding plans in your area…
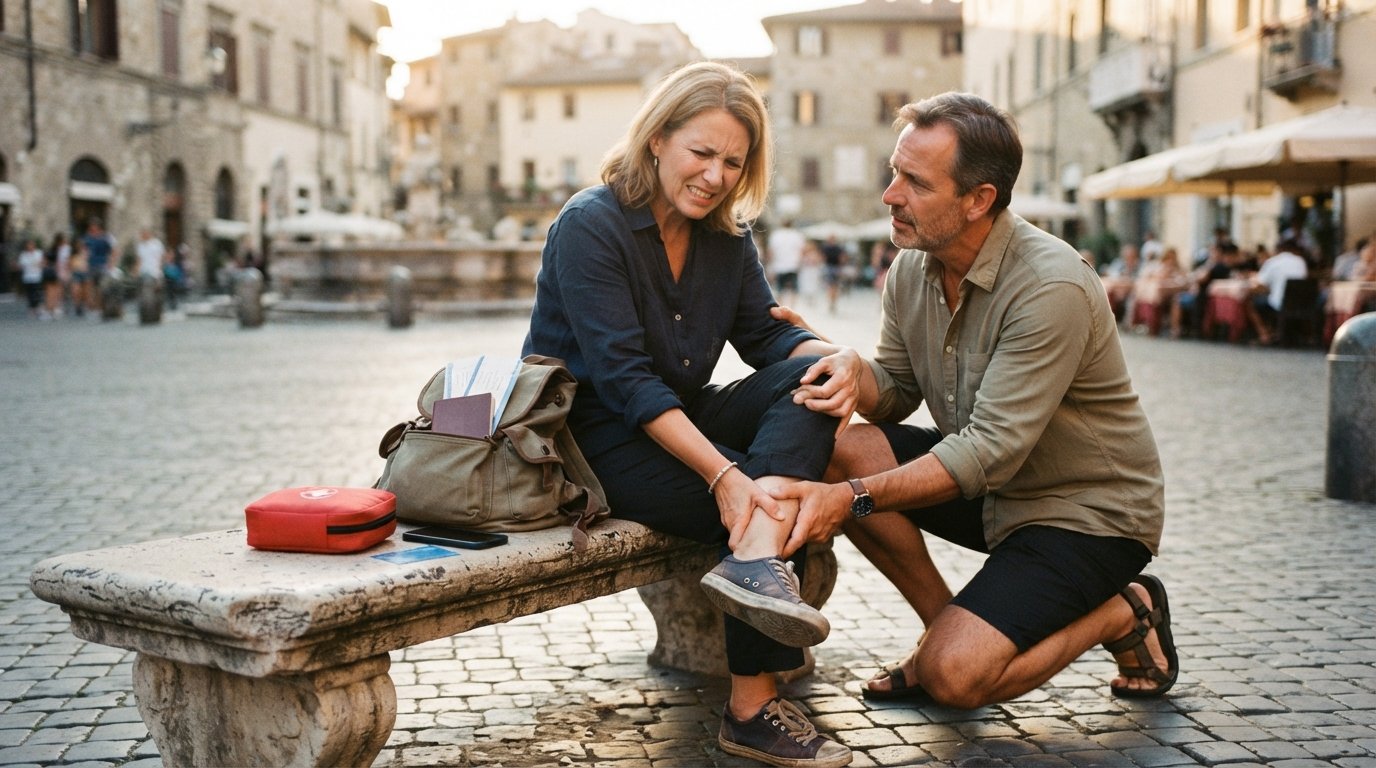
You have finally booked that dream trip to Italy, or perhaps a river cruise through Germany, and then a quiet worry creeps in: what happens if you break a leg in Rome or need a doctor in Tokyo? Original Medicare, the federal health insurance you rely on at home, offers almost no protection once you leave the United States. That is where Medicare foreign travel emergency coverage Medigap becomes essential. Certain Medicare Supplement plans, also called Medigap, include a foreign travel emergency benefit that can pay a substantial share of emergency medical costs outside the country. Understanding how this benefit works, which plans include it, and when it applies can mean the difference between a manageable bill and a financial shock during what should be a relaxing vacation.
This guide walks through the details of Medigap foreign travel emergency coverage, the limits you should expect, and the steps to take before you travel. You will also learn how this benefit interacts with other Medicare coverage and how to compare plans through trusted resources like NewMedicare.com. By the end, you will know exactly how to protect yourself and your wallet when you cross the border.
What Original Medicare Covers Outside the United States
Original Medicare (Part A and Part B) generally does not pay for health care services received outside the United States and its territories. There are a few narrow exceptions. Medicare may cover emergency inpatient hospital care in a foreign hospital if you are traveling through Canada on a direct route between Alaska and another U.S. state, or if you live in the U.S. and the foreign hospital is closer than the nearest U.S. hospital that can treat your emergency. In rare cases, Medicare may also cover medically necessary services on a ship within U.S. waters. Beyond these exceptions, you are on your own.
This limitation catches many beneficiaries off guard. If you have a heart attack in Paris, Original Medicare will not pay the hospital bill. If you need an emergency appendectomy in Mexico, you will face the full cost. Even Medicare Advantage plans, which sometimes offer limited worldwide emergency coverage, vary widely in how much they pay and under what circumstances. That gap is precisely why Medigap foreign travel emergency coverage exists.
It is also worth noting that Medicare Part D prescription drug plans rarely cover drugs purchased outside the U.S. So even if your emergency care is partially covered, your medications may not be. A comprehensive travel strategy should account for both medical and prescription needs.
Which Medigap Plans Include Foreign Travel Emergency Coverage
Not every Medigap plan includes the foreign travel emergency benefit. Only Plan C, Plan D, Plan F, Plan G, Plan M, and Plan N include it as a standard feature. Plans A, B, and K do not. If you are enrolled in one of the plans that includes the benefit, you automatically have access to it; you do not need to buy a separate rider. However, you must still meet the plan's deductible and other conditions before the benefit pays.
The benefit typically covers 80 percent of the cost of emergency care received during the first 60 days of each trip abroad, after you pay a deductible of $250. The maximum lifetime benefit is $50,000. That means once you have received $50,000 in foreign travel emergency benefits over your lifetime, the benefit is exhausted. For many travelers, that cap is more than sufficient for a single emergency, but it is not unlimited. If you take frequent international trips and have a serious medical event, you could reach the lifetime limit.
It is crucial to understand that this benefit applies only to emergency care. Routine checkups, elective procedures, and non-emergency services are not covered. The care must begin during the first 60 days of your trip and must be needed to treat an injury or illness that arose unexpectedly. If you plan to seek medical treatment abroad for a pre-existing condition or a scheduled procedure, Medigap will not help.
For beneficiaries who travel often or who want peace of mind, Plan G and Plan N are popular choices because they include the foreign travel emergency benefit along with other comprehensive coverage. Plan G, in particular, has become the go-to Medigap plan for new enrollees because it offers strong protection with predictable costs. You can explore plan options and compare quotes through NewMedicare.com to see which Medigap plan fits your travel habits and budget.
How the 80/20 Split Works in Practice
Imagine you are hiking in Switzerland and suffer a fall that requires an emergency room visit and a short hospital stay. The total bill comes to $10,000. After you pay the $250 deductible, Medigap will cover 80 percent of the remaining $9,750, which is $7,800. You would be responsible for the remaining $1,950, plus the deductible. That is a far cry from paying the full $10,000 out of pocket. The 80/20 split continues until you reach the $50,000 lifetime maximum.
Keep in mind that the deductible is per trip, not per year, and it applies separately from your plan's standard deductible for domestic care. Also, the 60-day window begins on the first day of your trip, not the first day you receive care. If you are traveling for six months, only emergencies that occur in the first 60 days are covered. After that, you are on your own unless you have separate travel insurance.
What to Do Before You Travel Abroad
Planning ahead is the single best way to avoid surprises. Before you leave the country, take these steps to ensure your Medigap foreign travel emergency coverage will work when you need it.
- Confirm your plan includes the benefit. Check your Medigap policy documents or call your insurer. If you have Plan A, B, or K, you do not have foreign travel emergency coverage. If you have Plan C, D, F, G, M, or N, you do.
- Carry your Medigap card and policy information. Keep a copy in your wallet and a digital copy on your phone. You will need to provide this information to the foreign hospital or doctor, and later to file a claim.
- Understand the claims process. In most cases, you will need to pay the foreign provider upfront and then submit a claim to your Medigap insurer for reimbursement. Keep all receipts and medical records. Some insurers may require you to file within a certain timeframe, often 90 days to one year.
- Consider a standalone travel insurance policy. Medigap foreign travel emergency coverage is helpful but limited. A comprehensive travel insurance policy can fill gaps such as medical evacuation, repatriation, and coverage beyond the 60-day window or $50,000 lifetime cap.
- Check your Medicare Advantage plan if you have one. Some Medicare Advantage plans offer worldwide emergency coverage, but the details vary. If you are in a Medicare Advantage plan, review your plan's evidence of coverage for foreign travel benefits.
Even with Medigap, you should budget for some out-of-pocket costs. The 20 percent coinsurance and the $250 deductible are your responsibility. For a very expensive emergency, that 20 percent could still be thousands of dollars. Travel insurance can help cover that remainder and often includes other valuable protections like trip cancellation and lost luggage.
If you are unsure whether your current Medigap plan includes foreign travel emergency coverage, or if you are shopping for a new plan, a licensed agent can walk you through the details. NewMedicare.com connects you with certified agents who can compare Medigap plans from leading carriers and help you find one that matches your travel plans and budget. There is no obligation, and the service is free.
How Medigap Foreign Travel Emergency Coverage Compares to Travel Insurance
Medigap foreign travel emergency coverage and standalone travel insurance serve different purposes, and many travelers benefit from having both. Medigap's benefit is designed to handle emergency medical costs during the early part of a trip, up to a lifetime maximum. Travel insurance, on the other hand, can cover a much broader range of situations, including medical evacuation, repatriation of remains, trip interruption, and even non-medical issues like lost passports or delayed flights.
One key difference is that Medigap's foreign travel benefit has a lifetime cap of $50,000, while travel insurance policies often have medical expense limits of $100,000 or more, and some offer unlimited medical evacuation. Travel insurance also typically covers care beyond the first 60 days of a trip, which is important for extended travelers. Additionally, travel insurance can provide coverage for pre-existing conditions if you purchase it within a certain window after booking your trip, whereas Medigap's foreign travel benefit excludes pre-existing conditions entirely.
Another distinction is the claims process. With Medigap, you generally pay upfront and seek reimbursement. Many travel insurance policies also require upfront payment, but some offer direct payment to providers or 24/7 assistance hotlines that can coordinate care. If you are traveling to a remote area or a country with a complex medical system, that support can be invaluable.
For most Medicare beneficiaries who travel abroad, the ideal approach is to have a Medigap plan that includes foreign travel emergency coverage and to purchase a separate travel insurance policy for each trip. This layered strategy ensures that you have both immediate emergency coverage and broader protection for the unexpected.
Medigap vs. Medicare Advantage for Foreign Travel
If you are enrolled in a Medicare Advantage plan instead of Original Medicare with Medigap, your foreign travel coverage will depend on your specific plan. Some Medicare Advantage plans offer emergency coverage worldwide, but the copayments and coinsurance can be higher than what Medigap offers. Others provide no foreign coverage at all. It is essential to read your plan's evidence of coverage carefully. If you travel frequently and want predictable foreign emergency coverage, Original Medicare with a Medigap plan that includes the benefit may be a better fit. You can compare Medigap and Medicare Advantage options side by side using the tools at NewMedicare.com.
Common Misconceptions About Medigap Foreign Travel Coverage
Many beneficiaries assume that Medigap foreign travel emergency coverage works just like domestic coverage. It does not. Understanding the differences can save you from unpleasant surprises.
One common misconception is that the benefit covers all medical care abroad. In reality, it only covers emergency care received during the first 60 days of a trip. If you are diagnosed with a chronic condition while traveling and need ongoing treatment, that treatment is not covered. Similarly, if you need a follow-up appointment after an emergency, that follow-up may not be covered unless it is part of the emergency episode.
Another misconception is that the $50,000 lifetime maximum is per trip. It is not. It is a lifetime maximum across all trips. Once you have received $50,000 in benefits, the coverage ends permanently. For most people, that is still a substantial safety net, but it is important to know the limit.
Some beneficiaries also believe that Medigap will pay foreign hospitals directly. In most cases, you will need to pay the hospital or doctor yourself and then file a claim for reimbursement. This means you should have access to funds or a credit card with a high limit in case of an emergency. Travel insurance with a direct-pay option can be a helpful supplement.
Finally, many people do not realize that Medigap foreign travel emergency coverage does not include medical evacuation. If you need to be airlifted from a remote area to a major hospital, that cost could be tens of thousands of dollars and is not covered by Medigap. Travel insurance or a medical evacuation membership is essential for that protection.
How to File a Claim for Foreign Travel Emergency Care
Filing a claim for foreign travel emergency care under Medigap is similar to filing a claim for domestic care, but there are a few extra steps. First, you will need to pay the foreign provider at the time of service. Request an itemized bill and a detailed medical report, preferably in English or with a certified translation. Take photos of everything and keep copies.
Next, contact your Medigap insurer as soon as possible to notify them of the claim. They will provide you with a claim form and instructions. You will typically need to submit the itemized bill, proof of payment, and the medical report. Some insurers may also require a statement from the treating physician explaining the nature of the emergency.
Be prepared for a wait. Reimbursement can take several weeks or even months, depending on the insurer and the complexity of the claim. Follow up regularly and keep records of all correspondence. If your claim is denied, ask for the reason in writing and consider appealing if you believe the denial is incorrect.
It is also a good idea to notify your Medigap insurer before you travel if you know you will be abroad for an extended period. Some insurers offer assistance services or can provide guidance on how to handle potential claims. While not required, it can streamline the process if something goes wrong.
For beneficiaries who want help understanding their Medigap plan's foreign travel benefits or who need assistance finding a plan that includes this coverage, NewMedicare.com offers free, no-obligation quotes and access to licensed agents. You can also explore educational resources on Medicare emergency room visits to better understand how emergency care works under different Medicare plans.
Key Takeaways for Traveling with Medigap
Medicare foreign travel emergency coverage through Medigap is a valuable benefit for beneficiaries who travel outside the United States. It can save you tens of thousands of dollars in the event of a sudden illness or injury. However, it is not a substitute for comprehensive travel insurance, and it comes with important limitations.
To make the most of this benefit, confirm that your Medigap plan includes it, understand the deductible and coinsurance, and know the lifetime maximum. Carry your policy information with you, and be prepared to pay upfront and seek reimbursement. Consider purchasing travel insurance to cover medical evacuation, repatriation, and care beyond the 60-day window. And if you are unsure whether your current coverage is adequate, speak with a licensed agent who can help you compare options.
Travel should be a time of joy and discovery, not financial stress. With the right preparation and the right Medigap plan, you can explore the world with confidence, knowing that a safety net is in place. Whether you are planning a short trip to Canada or a months-long adventure through Asia, understanding your Medicare foreign travel emergency coverage Medigap is an essential part of your travel checklist. NewHealthInsurance
Compare health plans
Finding plans in your area…