Medicare Coverage for Podiatry Foot Care: What's Covered
Medicare covers medically necessary podiatry but excludes routine foot care. Call (833)-864-8213 to compare plans that include foot care benefits.
Compare health plans
Finding plans in your area…
Your feet carry you through decades of life, and when they hurt, everything else suffers. If you are enrolled in Medicare and wondering whether a visit to the podiatrist will be paid for, the answer is more nuanced than a simple yes or no. Medicare does cover medically necessary podiatry services, but it draws a sharp line between treating disease and trimming toenails. Understanding that line, and knowing how to document your condition, can save you from surprise bills and help you get the care you need.
The rules hinge on why you need care, not just what service is performed. A diabetic with nerve damage who needs a callus shaved is in a very different category from a healthy retiree who wants a cosmetic pedicure. This guide walks through the coverage rules, the qualifying conditions, the documentation podiatrists must submit, and the practical steps for finding a provider who accepts Medicare. It also explains where Medicare Advantage plans can fill gaps and how to estimate your out-of-pocket costs before you book an appointment.
How Medicare Part B Treats Podiatry Services
Original Medicare is split into Part A for hospital care and Part B for outpatient medical services. Podiatry falls almost entirely under Part B. That means you pay the Part B premium, meet the annual deductible, and then generally owe 20 percent of the Medicare-approved amount for covered services. The critical question is whether the service is considered medically necessary treatment of a disease or injury rather than routine maintenance.
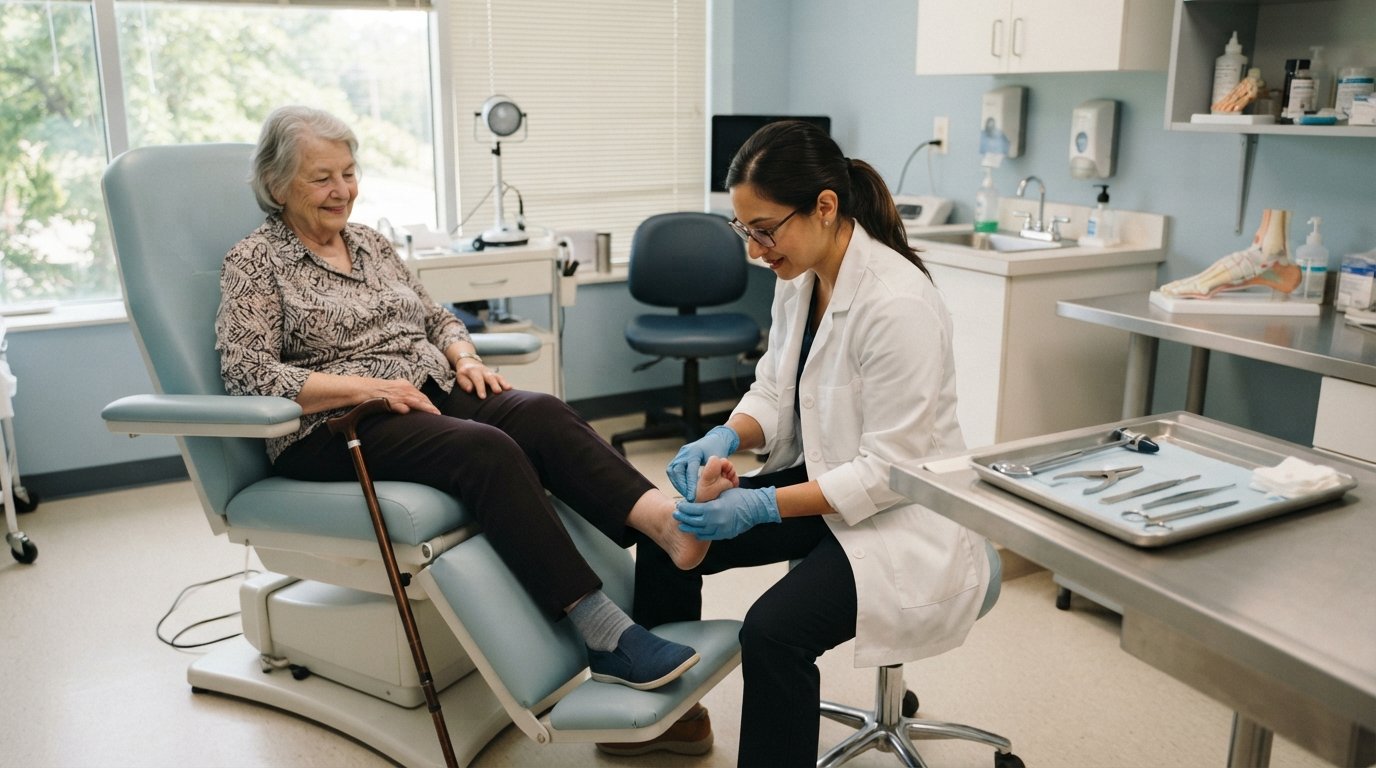
Medicare defines routine foot care as services like clipping nails, cutting calluses, and trimming corns in the absence of a systemic condition that puts your feet at risk. Those services are excluded from coverage by statute. However, the same physical actions can become covered when they are performed to treat a documented medical condition. For example, a podiatrist debriding a diabetic foot ulcer is treating a disease. A podiatrist trimming the same patient's nails may be covered only if the patient has a qualifying systemic condition and the documentation supports medical necessity.
This distinction matters because podiatry offices bill Medicare differently depending on the diagnosis. A routine nail trim submitted with a routine foot care code will be denied. The same trim submitted with a supporting diagnosis, such as diabetic peripheral neuropathy with loss of protective sensation, may be paid. The coverage decision rests on the medical record, not the procedure alone. That is why patients who understand the documentation requirements tend to have smoother claims experiences.
When Routine Foot Care Is Excluded
Routine foot care is one of the clearest exclusions in the Medicare benefit. If you do not have a systemic condition that affects your feet, Medicare will not pay for nail clipping, corn or callus removal, or hygienic foot care. This exclusion exists because these services are considered maintenance rather than treatment of illness or injury. Many beneficiaries are surprised by this, especially if they have had foot care covered under a previous employer plan or Medicaid.
The exclusion is not absolute. Medicare's policy manual lists specific systemic conditions that, when present and documented, can make routine foot care covered. The most common is diabetes with peripheral neuropathy. Others include chronic venous insufficiency, peripheral arterial disease, and certain neurological conditions. The key is that the condition must be severe enough to create a risk of complications, and the podiatrist must document the condition and the reason the foot care is medically necessary. Without that documentation, the claim will be denied even if the patient genuinely needs the service.
It is also worth noting that Medicare does not cover flatfoot care, orthotics for flat feet, or routine shoe inserts unless a specific medical condition qualifies. Custom therapeutic shoes for diabetics are a separate benefit with their own rules. Beneficiaries should ask their podiatrist upfront whether a planned service is likely to be covered and what documentation will be submitted. A frank conversation before the appointment prevents most billing surprises.
Qualifying Conditions and Documentation Requirements
To qualify for covered podiatry care, you generally need a condition that affects circulation, sensation, or structural integrity of the foot. Diabetic peripheral neuropathy is the most frequently cited qualifier. When diabetes causes nerve damage and loss of protective sensation, even a minor callus can become an ulcer, and an ulcer can lead to amputation. Medicare recognizes this risk and covers medically necessary foot care for these patients.
Other qualifying conditions include peripheral arterial disease, which impairs blood flow to the feet, and chronic venous insufficiency, which can cause swelling and skin breakdown. Structural deformities such as bunions, hammertoes, and bone spurs can also qualify when they cause pain or functional limitation and are treated medically rather than cosmetically. The podiatrist must document the condition, the symptoms, and the medical rationale for the service. This documentation typically includes a history and physical, diagnostic tests where appropriate, and a treatment plan.
Medicare also requires that the podiatrist document the class of findings for routine foot care. The Medicare Benefit Policy Manual describes classes of findings, ranging from a Class A finding (no systemic condition) to a Class D finding (severe systemic condition with significant risk). Coverage for routine foot care generally requires a Class B or higher finding, along with a documented systemic condition. The podiatrist must also note the date of the most recent evaluation and the specific services performed. Patients can help by bringing a list of medications, recent lab results, and any prior podiatry records to the appointment.
If you have diabetes, Medicare also covers therapeutic shoes and inserts once per calendar year when prescribed by a podiatrist or other qualified physician and furnished by a certified supplier. This is a separate benefit from routine foot care and has its own documentation requirements. Beneficiaries should ask their podiatrist whether they qualify and where to obtain the shoes. The coverage can make a meaningful difference in preventing foot ulcers and keeping patients mobile.
How Medicare Advantage Plans Can Add Routine Foot Care
Medicare Advantage plans are private plans that provide at least the same benefits as Original Medicare, but many offer additional benefits that Original Medicare does not cover. Routine foot care is one of the most common extra benefits. If you are enrolled in a Medicare Advantage plan, check your plan's summary of benefits to see whether routine foot care is included and what limits apply. Some plans cover a certain number of visits per year, while others cover routine care with a copay.
These extra benefits can be valuable for beneficiaries who need regular nail care or callus removal but do not meet the strict Original Medicare criteria. However, the details matter. A plan might cover routine foot care only when provided by an in-network podiatrist, or it might require a referral from your primary care physician. Some plans limit the benefit to diabetics, while others extend it to all members. Reading the evidence of coverage carefully, or calling the plan's member services line, will clarify exactly what is available.
Medicare Advantage plans also vary in how they handle prior authorization for podiatry services. Some plans require prior authorization for non-routine foot surgery or for custom orthotics, while others do not. Beneficiaries should confirm the process before scheduling a procedure. If you are comparing Medicare Advantage plans and want to know which ones include routine foot care, a licensed agent can help you review the options in your ZIP code. NewMedicare.com offers a free plan comparison tool that shows the benefits each plan includes, including podiatry and other ancillary services.
For beneficiaries who want the broadest possible access to podiatrists, Original Medicare combined with a Medigap plan may be the better fit. Medigap plans do not add routine foot care benefits, but they do help cover the 20 percent coinsurance that Original Medicare leaves behind. That can make covered podiatry services more affordable. If you are considering a Medigap plan, it is worth reviewing how the different letter plans handle coinsurance and whether the plan is available in your state.
Finding a Podiatrist Who Accepts Medicare
Not every podiatrist accepts Medicare, and those who do may not accept assignment on every service. A podiatrist who accepts assignment agrees to charge no more than the Medicare-approved amount for covered services. A podiatrist who does not accept assignment can charge up to 15 percent more than the approved amount, and you may be responsible for the difference. Before you book an appointment, ask two questions: Do you accept Medicare? Do you accept assignment?
Finding an in-network podiatrist is straightforward if you are in Original Medicare, because Original Medicare does not use networks. Any podiatrist who accepts Medicare can see you, and you can use the Medicare Plan Finder or the Medicare.gov care compare tool to search for podiatrists in your area. If you are in a Medicare Advantage plan, you generally need to use the plan's network, although some plans offer out-of-network benefits. The plan's provider directory will list in-network podiatrists, and you should confirm with the office that they are still in the network before scheduling.
Referrals are another consideration. Original Medicare generally does not require a referral to see a podiatrist, but some Medicare Advantage plans do. If your plan requires a referral, ask your primary care physician to provide one before your visit. Without it, the plan may deny the claim even if the service would otherwise be covered. It is also wise to ask the podiatrist's office whether they will verify your eligibility and benefits before the appointment. A good office will do this as a courtesy and can tell you what your expected out-of-pocket cost will be.
When you call to schedule, have your Medicare card and, if applicable, your Medicare Advantage or Medigap card ready. Ask whether the podiatrist is accepting new Medicare patients and whether there is a wait for appointments. If you have a qualifying condition, mention it so the office can note it in your record. This is also a good time to ask about the practice's billing policies, including whether they require payment upfront for non-covered services. Being proactive about these details prevents most billing headaches.
Cost Expectations for Covered and Non-Covered Foot Care
For covered podiatry services under Original Medicare, you generally pay the Part B deductible first, then 20 percent of the Medicare-approved amount. The Part B deductible changes annually, so check the current amount before your appointment. If you have a Medigap plan, it may cover some or all of that 20 percent, depending on the plan letter. If you have a Medicare Advantage plan, your cost sharing depends on the plan's copay or coinsurance for podiatry services, which can vary widely.
For non-covered routine foot care, you will pay the full charge out of pocket. Podiatry offices set their own fees for routine services, and those fees can range from modest to significant depending on the region and the practice. Some offices offer a cash discount for routine care, and some Medicare Advantage plans reimburse a portion of routine foot care even if the provider is out of network. It is worth asking about these options if you need routine care but do not qualify for coverage under Original Medicare.
There are also financial assistance programs that can help with Medicare costs. State Pharmaceutical Assistance Programs and Medicare Savings Programs can help with premiums and cost sharing for eligible beneficiaries. If you have limited income and resources, you may qualify for help paying your Part B premium and deductibles. These programs are administered by state Medicaid agencies and Social Security, and eligibility varies by state. A licensed agent or your local State Health Insurance Assistance Program can help you determine whether you qualify.
For beneficiaries who want to compare Medicare Advantage plans that include routine foot care, or who want to understand how Medigap plans can reduce their out-of-pocket costs for covered podiatry services, NewMedicare.com provides free, no-obligation plan comparisons. You can enter your ZIP code and review the plans available in your area, including their podiatry benefits and cost sharing. The platform also connects you with licensed insurance agents who can answer specific questions about coverage and help you enroll. If you are also thinking about life insurance to protect your family's finances, BetterLifeQuote offers a simple way to compare quotes from participating carriers in one request, with licensed agents available to help you find coverage that fits your budget.
Practical Steps Before Your Podiatry Appointment
Preparation makes the difference between a smooth claim and a denial. Start by reviewing your Medicare coverage and any supplemental plans you have. Confirm whether you are in Original Medicare, a Medicare Advantage plan, or a Medigap plan, and note the cost-sharing rules that apply. Then gather your medical records, including any documentation of diabetes, neuropathy, peripheral arterial disease, or other qualifying conditions. Bring a list of your medications and the names of your other doctors.
When you schedule the appointment, tell the office why you need care and ask whether the service is likely to be covered. Ask whether the podiatrist accepts assignment and whether prior authorization is required. If you are in a Medicare Advantage plan, confirm that the podiatrist is in network and that the plan covers the service. Ask what your expected out-of-pocket cost will be. These questions take only a few minutes and can prevent most surprises.
At the appointment, be clear about your symptoms and your medical history. Ask the podiatrist to document the medical necessity of the service in your record. If the service is not covered, ask for the charge in advance and whether there is a cash discount. If you need routine foot care and do not qualify for coverage, ask whether the office offers a payment plan or whether your Medicare Advantage plan provides any reimbursement. Being an informed patient is the best way to get the care you need without unnecessary financial stress.
Medicare coverage for podiatry foot care is not one-size-fits-all, but it is more predictable once you understand the rules. Covered services require a qualifying condition and proper documentation, while routine care is generally excluded unless you have a Medicare Advantage plan that adds the benefit. By knowing the difference, verifying your provider's Medicare status, and asking the right questions before your visit, you can protect both your feet and your wallet. If you need help comparing plans or understanding your options, a licensed agent can walk you through the choices available in your area.
Compare health plans
Finding plans in your area…