Medicare Coverage for Mental Health Counseling Sessions
Medicare coverage for mental health counseling sessions depends on provider type and plan. Call (833)-864-8213 to confirm your therapy costs before booking.
Compare health plans
Finding plans in your area…
When stress, grief, or a persistent mental health condition starts affecting daily life, the first question many beneficiaries ask is simple: will Medicare pay for therapy? The answer is usually yes, but the details matter. Medicare coverage for mental health counseling sessions spans outpatient visits, intensive programs, and prescription drugs, yet each piece follows its own rules for providers, settings, and cost sharing. Understanding those rules before you book an appointment can save you hundreds of dollars and help you avoid surprise bills.
This guide walks through how Original Medicare (Part B) handles counseling, how Medicare Advantage plans approach in-network providers, and where Part D fits in for psychiatric medications. It also explains the difference between psychiatrists, psychologists, and licensed counselors, because Medicare treats them differently. By the end, you should know exactly what to check before your first session and how to confirm your costs in advance.
Outpatient Mental Health Coverage Under Part B
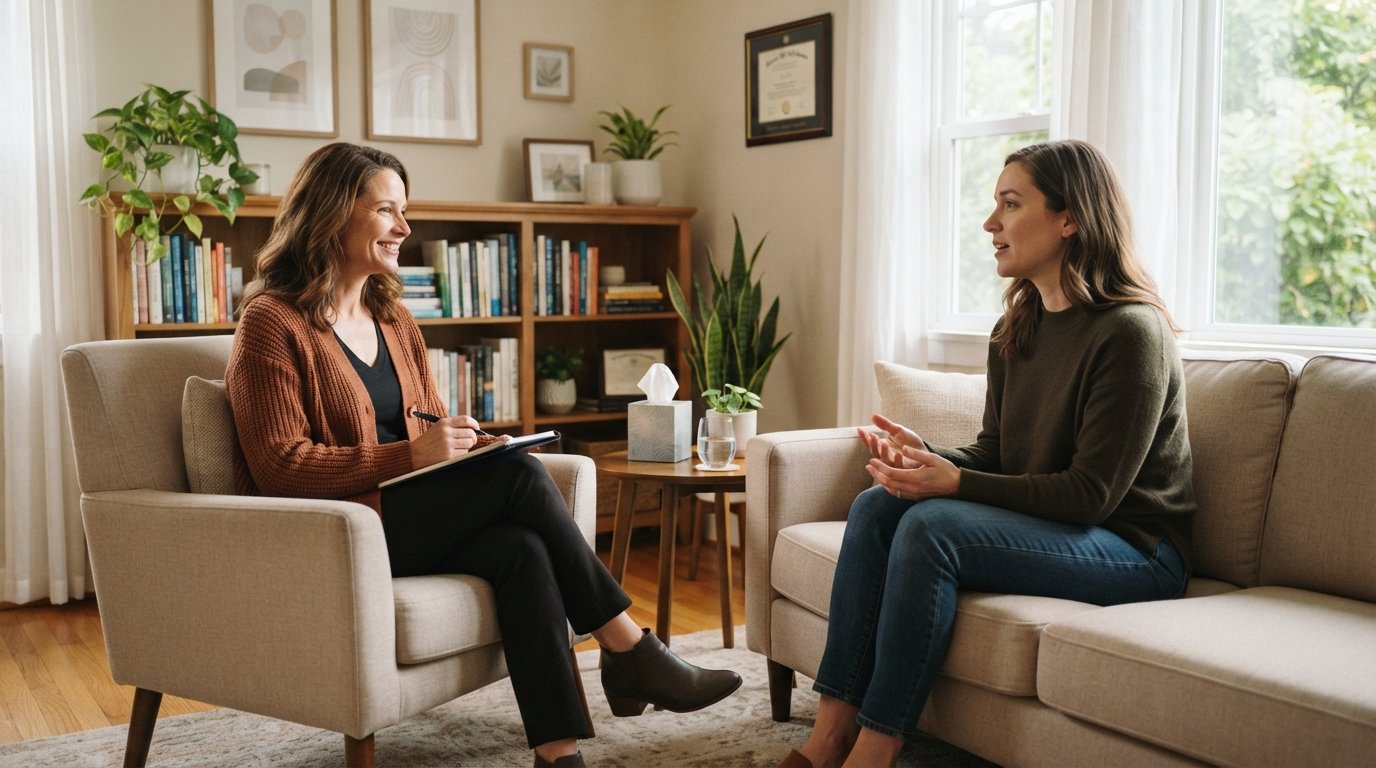
Original Medicare Part B covers outpatient mental health services, including counseling sessions with qualified providers. This is the foundation of Medicare coverage for mental health counseling sessions. Coverage includes individual therapy, group therapy, family counseling (when it is directly related to your treatment), and diagnostic evaluations. Part B also covers outpatient visits with psychiatrists and certain other practitioners, plus intensive outpatient programs and partial hospitalization when medically necessary.
Cost sharing works differently for outpatient therapy than for most other Part B services. For a Medicare-approved therapist, you generally pay 20 percent of the Medicare-approved amount after the Part B deductible, and Medicare pays 80 percent. However, for outpatient mental health services in a hospital setting, the coinsurance can be higher, so setting matters. Always ask whether your session will be billed as an office visit or a hospital outpatient service, because the second can cost you more.
There is also a lifetime limit on how much Medicare will pay for certain hospital-based mental health services. Part B helps pay for a limited number of days in a specialty psychiatric hospital over your lifetime. After that limit is reached, you may be responsible for all costs. For routine weekly counseling, though, this limit rarely comes into play. The bigger issue for most beneficiaries is finding a provider who accepts Medicare assignment, meaning they agree to charge no more than the Medicare-approved amount.
One practical step: before your first appointment, call the provider's office and ask two questions. First, are you a Medicare-enrolled provider? Second, do you accept assignment? If the answer to the first is no, Medicare will not pay for the session at all. If the answer to the second is no, you may be billed the difference between the provider's charge and the Medicare rate, which can add up quickly over a year of weekly sessions.
Psychiatrists, Psychologists, and Licensed Counselors: Who Medicare Pays
Not every mental health professional is treated the same under Medicare. This is one of the most confusing parts of Medicare coverage for mental health counseling sessions, and it trips up many beneficiaries who assume any licensed therapist is covered. The rules hinge on the provider's credentials and whether they are enrolled in Medicare as an eligible supplier.
Psychiatrists are medical doctors, so their services are covered under Part B like any other physician visit. Psychologists are also covered by Part B when they are Medicare-enrolled, and their services fall under the same general cost-sharing structure. Licensed clinical social workers and clinical nurse specialists are likewise recognized Medicare providers for mental health services. The gap appears with licensed professional counselors and marriage and family therapists: historically, Medicare did not cover these providers, and coverage rules have changed only gradually. Some licensed counselors now qualify, but enrollment status and state rules still vary, so verification is essential.
Here is a quick way to think about the provider landscape:
- Psychiatrists: Covered under Part B as physicians; can prescribe medication and provide therapy.
- Psychologists: Covered under Part B when enrolled; provide testing and therapy but generally cannot prescribe.
- Licensed clinical social workers: Covered under Part B when enrolled; provide counseling and case management.
- Licensed professional counselors and marriage and family therapists: Coverage has expanded but is not universal; confirm Medicare enrollment before booking.
Because eligibility varies by credential and enrollment, the safest approach is to ask for the provider's Medicare enrollment status in writing or verify it through the provider's billing office. If a counselor is not enrolled, you may still see them, but you will pay out of pocket, and those costs will not count toward your Part B deductible or coinsurance.
Intensive Outpatient Programs and Partial Hospitalization
For beneficiaries whose needs go beyond weekly talk therapy, Medicare covers more structured treatment through intensive outpatient programs and partial hospitalization. These programs are designed for people who need several hours of treatment per week but do not require overnight stays. Part B covers partial hospitalization services, which typically include psychiatric evaluation, individual and group therapy, occupational therapy, and medication management, delivered in a hospital outpatient department or a community mental health center.
Intensive outpatient programs (IOPs) are a step down from partial hospitalization and usually involve several group sessions per week. Coverage depends on medical necessity and the setting. Medicare coverage for mental health counseling sessions in these programs follows the same logic as other outpatient care: Medicare pays its share of the approved amount, and you pay coinsurance. The exact percentage can differ between hospital-based and freestanding programs, so ask for a cost estimate before starting.
Medical necessity documentation matters here. The program will need to show that your condition requires this level of care, and your doctor's referral or evaluation usually supports that. If a program is not Medicare-certified, Medicare will not pay, no matter how appropriate the treatment is. Before enrolling, confirm that the facility participates in Medicare and ask how it bills for partial hospitalization versus standard outpatient visits.
Part D and Psychiatric Medications
Therapy is only part of the picture for many beneficiaries. Psychiatric medications, including antidepressants, anti-anxiety drugs, and mood stabilizers, are generally covered under Medicare Part D, not Part B. This distinction is important because Original Medicare alone does not cover most outpatient prescription drugs. If you take medication for a mental health condition, you need a Part D plan or a Medicare Advantage plan that includes drug coverage.
Part D formularies vary by plan, and not every psychiatric drug is covered on every formulary. Some plans place certain medications on higher tiers, which means higher copays. Before enrolling, check whether your specific medications are on the plan's formulary and what tier they fall under. If your drug is not covered, you or your prescriber can request an exception or a formulary alternative. This step is worth doing during the Annual Enrollment Period, because switching plans can change your drug costs significantly.
There is one exception worth knowing: certain medications administered in a doctor's office or hospital outpatient setting may be covered under Part B rather than Part D. For example, some injectable psychiatric medications given in a clinical setting fall under Part B. If you receive medication during a partial hospitalization program or an office visit, ask how it will be billed so you know which coverage applies.
Finding In-Network Providers Under Medicare Advantage
If you are enrolled in a Medicare Advantage (Part C) plan instead of Original Medicare, your mental health coverage generally follows the plan's network rules. Medicare Advantage plans must cover the same services as Original Medicare, including outpatient mental health care, but they can require you to use in-network providers and may require referrals for specialist care. That means Medicare coverage for mental health counseling sessions under Medicare Advantage depends heavily on whether your therapist is in the plan's network.
Before booking, check the plan's provider directory for your therapist's name and confirm the directory is current. Provider directories are often outdated, so a phone call to the plan or the therapist's office is the most reliable check. If your therapist is out of network, you may face higher costs or no coverage at all, depending on the plan. Some plans offer out-of-network benefits for mental health care, but those benefits usually come with higher cost sharing.
Medicare Advantage plans may also offer extra benefits beyond Original Medicare, such as telehealth counseling or wellness programs. These extras can make access easier, especially for beneficiaries in rural areas or those with mobility challenges. Ask your plan whether telehealth sessions with a licensed therapist are covered and what the cost sharing is. If you are comparing plans during enrollment, mental health provider access is a legitimate factor to weigh alongside premiums and drug coverage.
For a broader look at how Medicare coordinates with other coverage and providers, our guide on how Medicare works with other insurance providers explains the coordination rules that can affect your out-of-pocket costs.
Practical Steps to Confirm Your Coverage and Costs
Knowing the rules is useful, but confirming your specific situation is what prevents surprise bills. Medicare coverage for mental health counseling sessions can vary based on your plan type, your provider's enrollment status, and the setting where care is delivered. A short verification routine before your first appointment can save you money and frustration.
- Confirm the provider accepts Medicare. Ask for the provider's Medicare enrollment status and whether they accept assignment.
- Ask how the visit will be billed. Office visit, hospital outpatient, or telehealth, because the cost sharing can differ.
- Check your plan's network if you have Medicare Advantage. Verify the therapist is in network and whether a referral is needed.
- Review your Part D formulary. Make sure your psychiatric medications are covered and check the tier and copay.
- Request a written cost estimate. A reputable provider or plan can give you a reasonable estimate of your share before treatment begins.
After you confirm coverage, keep a simple record of each session, including the date, provider, and amount billed. If a claim is denied, you have the right to appeal, and documentation makes the process smoother. Medicare Advantage plans and Part D plans have specific appeal timelines, so act promptly if you receive a denial.
Costs can add up even with coverage, especially if you see a specialist weekly or take multiple medications. If you are also thinking about protecting your family's financial future, services like BetterLifeQuote let you compare life insurance quotes from participating carriers in one simple request, which can complement your health coverage planning.
What to Do If You Are Denied Coverage
Denials happen, but they are not always final. If Medicare or your Medicare Advantage plan denies a mental health service, read the denial notice carefully. It should state the reason and the appeal deadline. Common reasons include missing documentation of medical necessity, a provider who is not enrolled, or a service billed under the wrong code. Sometimes a simple correction by the provider's billing office resolves the issue.
If you need to appeal, gather supporting documents: your treatment plan, your provider's notes, and any prior authorization records. You can file an appeal yourself or ask your provider to help. For Medicare Advantage plans, the first level is a reconsideration by the plan, followed by an independent review if needed. Original Medicare has its own appeal process through the Medicare Administrative Contractor. Deadlines are strict, usually 60 days for a redetermination, so do not delay.
Prevention is better than appeal. Most denials stem from verification gaps that could have been caught before the first session. Confirming provider enrollment, network status, and billing codes upfront is the most reliable way to protect yourself.
Medicare coverage for mental health counseling sessions is broader than many beneficiaries expect, but it rewards preparation. Check your provider's status, understand your plan's network and formulary rules, and ask for cost estimates before treatment starts. With those steps, you can focus on your health instead of your bills.
Compare health plans
Finding plans in your area…