Medicare Coverage for Home Health Aide Services: 2026 Rules
Medicare covers home health aide services only with skilled care and homebound status. Call (833)-864-8213 to explore your options.
Compare health plans
Finding plans in your area…
When a parent or spouse needs help at home, the first question is often whether Medicare will pay for it. The answer is more nuanced than a simple yes or no. Medicare coverage for home health aide services exists, but it comes with strict conditions: the care must be medically reasonable and necessary, ordered by a physician, and delivered under a plan of care. Understanding these rules can mean the difference between covered visits and surprise bills. This guide breaks down exactly when Medicare pays for home health aides, what qualifies as skilled care versus custodial care, and what to do when coverage runs out.
Skilled Care vs. Custodial Care: The Core Distinction
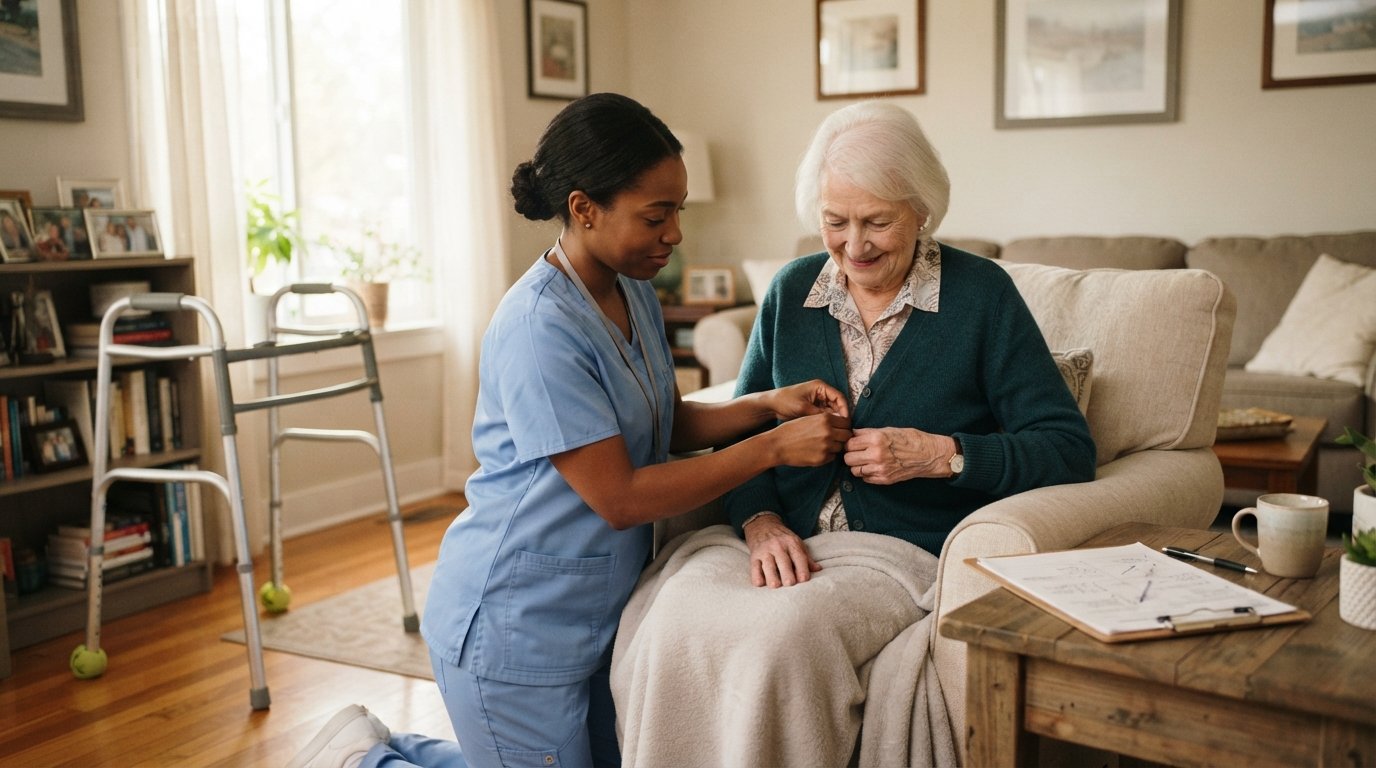
Medicare's home health benefit is built around skilled care. Skilled care means services that require the professional judgment of a nurse or therapist, such as wound care, medication management, or physical therapy. Custodial care, by contrast, involves help with activities of daily living (bathing, dressing, toileting) that can be safely performed by a non-professional. Medicare does not cover custodial care alone. However, if a beneficiary qualifies for skilled care, Medicare may also cover part-time or intermittent home health aide visits to assist with personal care.
The key is that the aide services must be part of a plan of care that includes skilled services. For example, if a patient is receiving skilled nursing care for a surgical wound, Medicare may cover an aide to help with bathing because the bathing is incidental to the skilled care. But if the only need is help with bathing, Medicare will not pay. This distinction is critical for families planning long-term care. Many people assume Medicare will cover ongoing personal care, but it is not designed for that purpose.
Another common misconception is that Medicare covers 24-hour home care. It does not. The home health benefit is for part-time, intermittent care. Typically, that means a few hours a day, a few days a week, and only while skilled services are medically necessary. Once the skilled need ends, the aide services end as well. This is why it is essential to understand the homebound requirement and the order requirements before assuming coverage will continue indefinitely.
The Homebound Requirement and Physician Orders
To qualify for Medicare coverage for home health aide services, the beneficiary must be homebound. Homebound does not mean bedridden. It means leaving home requires a considerable and taxing effort, or that leaving is medically contraindicated. A person can be considered homebound if they need the help of another person or a device (like a cane or walker) to leave, or if they have a condition that makes leaving risky. Occasional absences for medical appointments or religious services are allowed, but they must be infrequent and short. This requirement ensures that home health is a substitute for institutional care, not a convenience.
In addition to being homebound, the patient must have a face-to-face encounter with a physician or allowed non-physician practitioner (like a nurse practitioner) within 90 days before or 30 days after the start of home health services. This encounter must be related to the reason home health is needed. The physician must also certify that the patient is homebound and needs skilled services, and must establish and review a plan of care. The plan of care outlines the specific services needed, the frequency of visits, and the expected duration. Without a signed order and plan of care, Medicare will not pay for home health aide services.
It is also important to note that the home health agency must be Medicare-certified. Not all agencies are. Families should verify that the agency accepts Medicare and meets the Conditions of Participation. The agency will coordinate with the physician to develop the plan of care and will provide the services directly. If a beneficiary uses a non-certified agency, Medicare will not cover the costs. This is a common pitfall for families who hire private aides without checking certification.
Covered Services Under the Home Health Benefit
When a beneficiary meets the criteria, Medicare Part A and Part B cover a range of home health services. These include skilled nursing care, physical therapy, occupational therapy, speech-language pathology, and medical social services. Home health aide visits are covered when they are part of the plan of care and the patient is also receiving skilled care. The aide can help with personal care such as bathing, dressing, grooming, and toileting, but only if those tasks are necessary to maintain the patient's health or to facilitate treatment of the illness or injury.
Medical supplies and durable medical equipment (DME) related to the home health plan may also be covered. For example, if a patient needs a walker or a hospital bed, Medicare may pay for the rental or purchase if the equipment is medically necessary. However, DME is covered under a separate benefit with its own rules, including a 20% coinsurance. It is important to distinguish between services covered under the home health benefit (which are typically covered at 100% by Medicare) and those covered under Part B (which may require coinsurance).
In our guide on Does Medicare Cover In-Home Health Assessments? 2026 Guide, we explain how in-home assessments work and what to expect. That article provides a helpful complement to this one, especially for families navigating the initial evaluation process.
Here is a quick summary of what is typically covered when the home health criteria are met:
- Skilled nursing care, such as wound care, injections, and monitoring of vital signs
- Physical, occupational, and speech therapy
- Home health aide visits for personal care (bathing, dressing) when part of a skilled plan of care
- Medical social services to help with community resources
- Medical supplies and durable medical equipment related to the plan of care
It is important to remember that Medicare does not cover 24-hour care at home, meal delivery, or homemaker services (like cleaning and laundry) unless they are incidental to the skilled care. Families often need to supplement with private pay or other resources for those services.
When Medicare Stops: Medicaid and Private Pay Options
Medicare coverage for home health aide services is not indefinite. Once the skilled need ends, the aide visits will stop. This can be a difficult transition for families who have come to rely on the help. At that point, options include Medicaid, private pay, or long-term care insurance. Medicaid, for those who qualify financially, may cover some home and community-based services, including personal care. However, Medicaid eligibility varies by state and typically requires meeting income and asset limits. It is not a substitute for Medicare, but it can fill gaps for low-income beneficiaries.
Private pay is another option. Families can hire aides directly or through an agency. Costs vary widely depending on location and level of care. Long-term care insurance may also cover home care, but policies differ in what they cover and for how long. It is wise to review any existing long-term care policy to understand the benefits. For those without insurance, paying out of pocket can be expensive. The national median cost for a home health aide is over $5,000 per month for full-time care, according to Genworth's Cost of Care Survey.
Some beneficiaries may also qualify for Programs of All-Inclusive Care for the Elderly (PACE), which provides comprehensive care for frail seniors. PACE is available in some states and can cover home care. However, eligibility is limited to those who meet nursing home level of care and are 55 or older. Families should explore all options and consult with a financial advisor or elder law attorney to plan ahead.
How Medicare Advantage Plans Administer Home Health Benefits
If a beneficiary is enrolled in a Medicare Advantage (Part C) plan, the plan must cover at least the same home health services as Original Medicare. However, the plan may have different rules for how those services are delivered. For example, the plan may require prior authorization or use a specific network of home health agencies. It is important to check with the plan before starting services to ensure the agency is in-network and that the plan will approve the care. Some Advantage plans also offer additional home health benefits, such as telehealth or remote monitoring, as supplemental benefits.
Another consideration is that Medicare Advantage plans often manage care through a coordinated approach. The plan may assign a case manager who oversees the home health plan of care. This can be beneficial for some, but it also means that the plan has more control over the services authorized. Beneficiaries have the right to appeal if they believe services were wrongly denied. The appeals process for Medicare Advantage is similar to Original Medicare but follows the plan's specific procedures.
When comparing Medicare Advantage plans, it is worth reviewing how each plan handles home health. Some plans have stricter prior authorization requirements, while others may offer more flexibility. NewMedicare.com can help you compare plans in your area and understand the home health benefits each one offers. Their licensed agents can walk you through the details and help you find a plan that meets your needs. For those who also need life insurance, BetterLifeQuote provides a simple way to compare quotes from multiple carriers.
Practical Steps to Secure Home Health Aide Coverage
Securing Medicare coverage for home health aide services requires a proactive approach. Start by discussing your needs with your primary care physician. Ask for a referral to a Medicare-certified home health agency. The agency will conduct an assessment and coordinate with your doctor to develop a plan of care. Be sure to document your homebound status and the skilled need. Keep a log of symptoms and any changes in condition. This documentation can be helpful if you need to appeal a denial.
If you are denied coverage, do not give up. You have the right to appeal. The first step is to request a redetermination from the Medicare Administrative Contractor (MAC). The notice of denial will include instructions on how to appeal. You can also contact your State Health Insurance Assistance Program (SHIP) for free counseling. SHIP counselors can help you understand your rights and navigate the appeals process. Many denials are overturned on appeal when proper documentation is provided.
Here is a checklist to help you get started:
- Talk to your doctor about your need for skilled care at home and ask for a home health order.
- Choose a Medicare-certified home health agency and verify that they accept Medicare.
- Ensure the agency develops a plan of care that includes aide services and that your doctor signs it.
- Keep records of all visits, services, and communications with the agency and your doctor.
- If denied, file an appeal promptly and seek help from SHIP or a patient advocate.
Remember that Medicare coverage for home health aide services is not automatic. It requires a team effort involving the patient, family, physician, and agency. Being informed and persistent can make a significant difference in obtaining the care you need.
Frequently Asked Questions
Does Medicare cover 24-hour home care?
No. Medicare covers only part-time, intermittent home health care. If you need around-the-clock care, you will need to explore other options such as private pay, Medicaid, or long-term care insurance.
What is the difference between home health aide and homemaker services?
Home health aides provide personal care such as bathing and dressing, which may be covered by Medicare if part of a skilled plan of care. Homemaker services include tasks like cleaning and cooking, which are not covered by Medicare.
Can I get home health aide services if I have a Medicare Advantage plan?
Yes, but the plan may have different rules, such as prior authorization or network restrictions. Check with your plan to understand your benefits.
Navigating Medicare coverage for home health aide services can be complex, but with the right information and support, you can access the care you need. For personalized assistance, consider reaching out to NewMedicare.com to compare plans and connect with a licensed agent who can guide you through the process.
Compare health plans
Finding plans in your area…