Medicare Coverage for Chiropractic Care: What's Covered
Medicare covers manual spinal manipulation for subluxations, but not maintenance care. Learn how to avoid denials and find plans with extra chiropractic benefits.
By Douglas Keaton
Compare health plans
Finding plans in your area…
If you rely on chiropractic adjustments to manage back pain, neck stiffness, or chronic headaches, you may wonder whether your Medicare benefits will help pay for those visits. The answer is not a simple yes or no. Medicare coverage for chiropractic care depends on the type of service you receive, the part of Medicare you have, and whether the treatment is considered medically necessary. Understanding these distinctions can save you from unexpected bills and help you build a care plan that works within your budget.
This article breaks down exactly what Original Medicare pays for, where Medicare Advantage and Medigap fit in, and how to avoid the most common coverage traps. Whether you are new to Medicare or reviewing your options during an enrollment period, the details below will help you ask the right questions and get the most from your benefits.
What Original Medicare Covers for Chiropractic Services
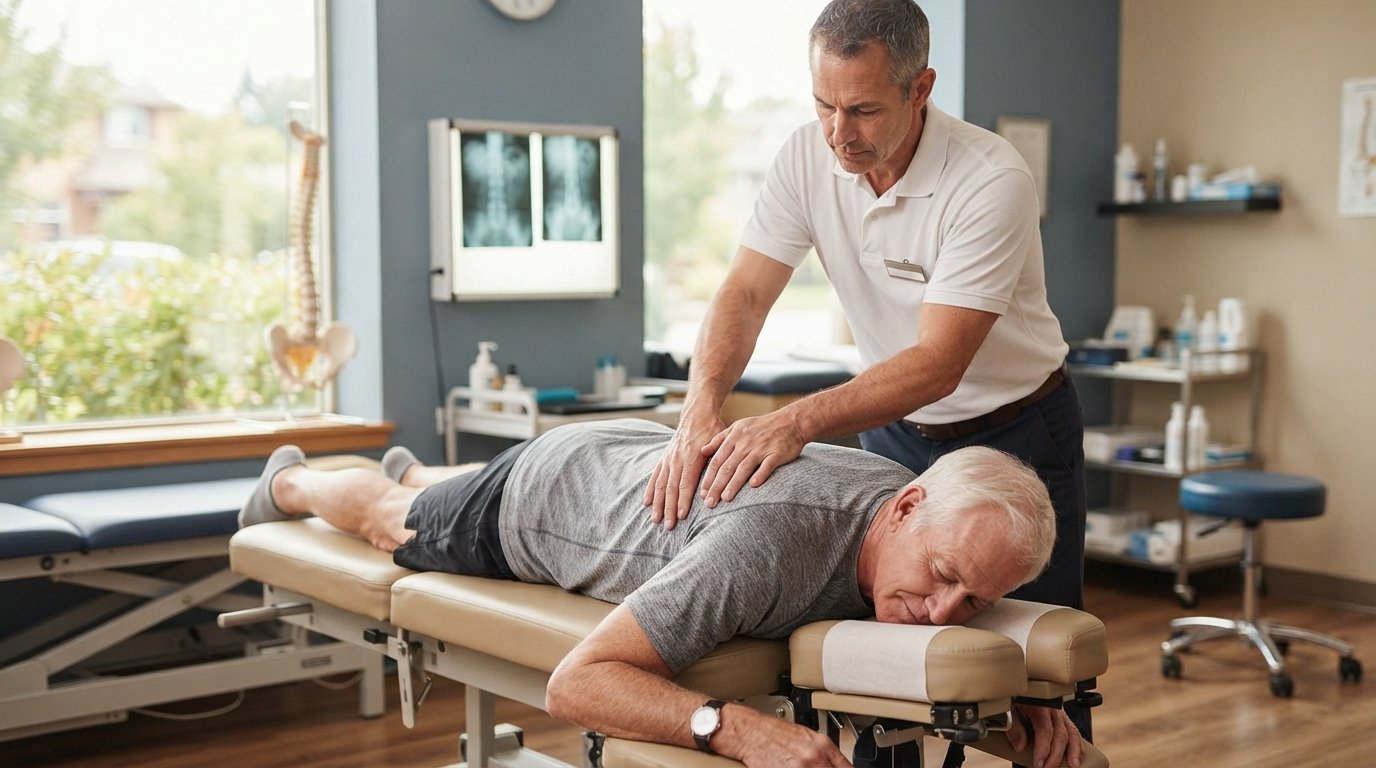
Original Medicare (Part A and Part B) covers a narrow slice of chiropractic care. Under Part B, Medicare will pay for manual manipulation of the spine to correct a subluxation. A subluxation is a misalignment of the vertebrae that a chiropractor can detect through physical examination or X-ray. The key word here is manual. Medicare does not cover chiropractic services that use electrical stimulation, ultrasound, diathermy, or other devices, even if those services are performed during the same visit. It also does not cover maintenance therapy, which is care designed to prevent future problems rather than treat an active condition.
To qualify for coverage, your chiropractor must be a licensed Medicare provider and must document that the manipulation is medically necessary to treat a specific spinal condition. If the treatment is considered maintenance or preventive, Medicare will deny the claim. This distinction trips up many beneficiaries because chiropractic care often blends active treatment with ongoing wellness visits. Your chiropractor should clearly state in your medical record that the manipulation is for an acute or chronic condition, not for general maintenance.
Medicare Part A, which covers hospital stays, rarely applies to chiropractic care unless you are admitted as an inpatient for a related condition. For the purposes of this article, Part B is the relevant coverage source for outpatient chiropractic visits. If you have not yet explored how Medicare works with other insurance providers, our guide on How Medicare Works With Other Insurance explains coordination of benefits in plain language.
What Counts as a Covered Chiropractic Service
Medicare uses a specific definition for covered chiropractic manipulation. The service must be performed by a chiropractor who is legally authorized to practice in your state and who has enrolled in Medicare. The manipulation must be manual, meaning the chiropractor uses their hands or a small instrument to apply controlled force to a spinal joint. The goal must be to improve function or reduce pain caused by a subluxation. If the chiropractor uses heat, cold, electrical stimulation, or traction, those services are not covered under the chiropractic benefit, though some may be covered under separate Part B benefits if ordered by a physician.
Medicare also limits the number of visits it will cover. There is no hard cap written into the law, but Medicare will only pay for services it deems medically necessary. If your chiropractor submits claims for visits that appear to be maintenance or routine, Medicare may deny them. You have the right to appeal a denial, but the process takes time and requires documentation. The best defense is a clear treatment plan that shows measurable progress toward a functional goal.
What Medicare Does Not Cover
Several common chiropractic services fall outside Medicare's coverage rules. These include:
- Maintenance or preventive adjustments
- X-rays ordered solely for chiropractic purposes (though some X-rays may be covered under Part B if medically necessary)
- Massage therapy, even when performed by a chiropractor
- Acupuncture, unless it is for chronic low back pain and meets specific criteria
- Nutritional supplements or herbal remedies
If you receive any of these services during a visit, you will likely be responsible for the full cost. Some chiropractors bundle covered and non-covered services into a single fee, which can create confusion. Always ask for an itemized statement and confirm which charges Medicare will pay before you agree to treatment.
How Medicare Advantage and Medigap Affect Chiropractic Coverage
If you have a Medicare Advantage (Part C) plan, your chiropractic coverage may be broader than what Original Medicare offers. Many Medicare Advantage plans include extra benefits such as routine chiropractic visits, acupuncture, and even massage therapy. These extras are one reason some beneficiaries choose Medicare Advantage over Original Medicare. However, the specifics vary widely by plan and by county. You must check your plan's evidence of coverage or provider directory to see what is included and what your copay will be.
Medigap plans (Medicare Supplement Insurance) do not add chiropractic benefits. Instead, they help pay your share of costs for services that Original Medicare covers. For example, if Medicare approves a chiropractic manipulation, Medigap may cover the 20 percent coinsurance you would otherwise owe. Medigap does not expand the list of covered services, so if Medicare denies a claim because the service is maintenance, Medigap will not pay either. Understanding this distinction is important when you compare plans.
Some beneficiaries with chronic back pain find that a Medicare Advantage plan with a generous chiropractic benefit is more cost-effective than paying out of pocket under Original Medicare. Others prefer the freedom of Original Medicare plus a Medigap plan, even if they pay more for chiropractic visits, because they want unrestricted access to specialists. There is no single right answer. It depends on your health needs, your budget, and the plans available in your ZIP code.
Comparing Costs Under Different Medicare Paths
To see how costs can differ, consider a hypothetical beneficiary who needs 12 chiropractic visits per year. Under Original Medicare, you would pay 20 percent of the Medicare-approved amount for each covered manipulation, plus any Part B deductible. If the chiropractor charges $80 per visit and Medicare approves $60, you would pay $12 per visit (20 percent of $60) after meeting your deductible. That adds up to $144 per year, not counting the deductible. If any visits are deemed maintenance, you would pay the full $80 for those.
Under a Medicare Advantage plan, you might pay a $20 copay per visit, or you might get a set number of visits for a flat fee. Some plans offer 12 or 20 visits per year with no copay. The trade-off is that Medicare Advantage plans often have networks, so you must see an in-network chiropractor. If you travel or want to see a specific provider, that limitation could matter. Medigap does not change the per-visit cost for chiropractic care because it only covers your share of Medicare-approved services.
When you compare plans, look beyond the premium. A plan with a low monthly premium might charge a high copay for chiropractic visits, while a plan with a higher premium might offer generous extras. If you see a chiropractor regularly, run the numbers. The same logic applies to other benefits like dental, vision, and hearing. For a broader look at how Medicare interacts with other coverage, including employer plans and retiree insurance, the guide mentioned earlier can help you avoid gaps.
Steps to Get Medicare to Pay for Chiropractic Care
Getting Medicare to cover your chiropractic visits requires more than just showing up at the office. You need to follow a process that documents medical necessity and ensures your provider is enrolled in Medicare. Here is a step-by-step approach that can improve your chances of coverage.
- Confirm that your chiropractor accepts Medicare. Not all chiropractors do. Some opt out of Medicare entirely, which means you pay out of pocket and cannot submit claims. Ask the office staff whether they are a participating provider or a non-participating provider. Participating providers accept Medicare's approved amount as full payment, while non-participating providers can charge up to 15 percent more.
- Get a clear diagnosis and treatment plan. Your chiropractor should document the specific condition being treated, such as a subluxation of the lumbar spine, and explain why manual manipulation is medically necessary. The plan should include measurable goals, such as reduced pain or improved range of motion. Avoid vague descriptions like "wellness care" or "maintenance."
- Ask for an Advance Beneficiary Notice (ABN) if there is doubt. If your chiropractor believes Medicare may deny a service, they should give you an ABN. This form explains why the service might not be covered and what you would pay if it is denied. If you sign an ABN, you accept financial responsibility. If you do not sign, the provider cannot bill you for the denied service.
- Keep records of every visit. Track the date, services provided, and any payments you make. If Medicare denies a claim, you will need this information to appeal. You can also use it to spot patterns, such as repeated denials for the same service, which might mean your chiropractor is coding the visits incorrectly.
- Appeal a denial if you believe it is wrong. Medicare denial letters include instructions for appeal. You generally have 120 days from the date of the denial notice to file a redetermination request. Include a letter from your chiropractor explaining why the service was medically necessary and any supporting documentation.
Following these steps does not guarantee coverage, but it puts you in a much stronger position. Medicare contractors look for evidence that the care is active treatment, not maintenance. If your chiropractor is unwilling to provide detailed documentation, you may want to find another provider. The extra effort upfront can save you hundreds of dollars in denied claims.
When Medicare Denies Chiropractic Claims and What to Do
Denials are common in chiropractic care because the line between active treatment and maintenance is not always clear. Medicare may deny a claim if the documentation does not show a specific subluxation, if the treatment plan lacks measurable goals, or if the visits appear to be routine. Sometimes the denial is simply a coding error. In other cases, Medicare may decide that your condition has stabilized and further manipulation is no longer medically necessary.
If you receive a denial, do not panic. Read the explanation carefully. It will tell you why the claim was denied and what you can do next. If the reason is a missing detail, your chiropractor can correct the claim and resubmit it. If the reason is medical necessity, you will need a stronger letter of support. You can also ask your primary care doctor to provide a referral or a statement explaining why chiropractic care is essential to your overall treatment plan.
Appeals can take weeks or months, so it helps to have a backup plan. If you have a Medicare Advantage plan, you may have broader coverage and a simpler appeals process. If you have Original Medicare, you might pay out of pocket while the appeal is pending. Some chiropractors offer payment plans or discounts for cash-paying patients. It is worth asking.
Another option is to explore whether your state has a chiropractic coverage mandate for private insurers. Some states require health plans to cover chiropractic care, but those rules do not apply to Medicare. Medicare is a federal program with its own rules. If you have other insurance in addition to Medicare, such as an employer plan or retiree coverage, that plan might pay for services Medicare denies. Coordination of benefits can get complicated, so it is smart to review how Medicare works with other insurance providers before you assume a denial is final.
How NewMedicare.com Can Help You Navigate Coverage
Understanding Medicare coverage for chiropractic care is just one piece of a larger puzzle. You also need to consider your prescription drug coverage, your hospital and medical benefits, and whether a Medicare Advantage or Medigap plan would serve you better. NewMedicare.com is a privately operated educational resource and service platform that helps individuals compare and enroll in Medicare plans. It offers unbiased information on Parts A, B, C, D, and Medigap, along with personalized plan comparisons and tools to connect you with licensed insurance agents.
If you are approaching 65, newly eligible due to a disability, or reviewing your options during the Annual Enrollment Period, NewMedicare.com can help you see which plans in your area include chiropractic benefits. You can request a complimentary, no-commitment quote by entering your ZIP code and answering a few questions. The process takes under five minutes, and a certified agent can walk you through the details. They can also help you understand how your chiropractic coverage interacts with other benefits, such as dental, vision, and hearing.
For those who want to explore broader health insurance options beyond Medicare, NewHealthInsurance.com is a digital platform that helps individuals, families, and small businesses find, compare, and enroll in affordable health insurance plans. It offers real-time quotes and state-specific guidance for all 50 states, covering plan types like ACA Marketplace, Medicare, and Short-Term insurance. If you are not yet eligible for Medicare or you need coverage for a family member, it can be a useful resource.
NewMedicare.com does not offer medical, legal, or financial advice. It is not affiliated with the U.S. government or the federal Medicare program. Its mission is to simplify the enrollment process and help you make informed decisions. Whether you need a stand-alone chiropractic benefit or a full Medicare Advantage plan with extras, the platform can connect you with a licensed agent who understands your local market.
Key Takeaways for Medicare Beneficiaries
Medicare coverage for chiropractic care is limited but not nonexistent. Original Medicare pays for manual manipulation of the spine to correct a subluxation when it is medically necessary. It does not cover maintenance therapy, massage, or devices. Medicare Advantage plans often include extra chiropractic visits, while Medigap plans only help with cost-sharing for covered services. To get the most from your benefits, confirm that your chiropractor accepts Medicare, document medical necessity, and appeal denials when appropriate.
If you see a chiropractor regularly, your choice of Medicare plan can make a big difference in your out-of-pocket costs. Take time during the next enrollment period to compare plans side by side. Look at the copays for chiropractic visits, the number of covered visits, and whether the plan requires a referral. A few minutes of research can save you hundreds of dollars and help you stay on track with your care. For personalized help, consider reaching out to a licensed agent through NewMedicare.com. They can answer your questions and help you find a plan that fits your health needs and your budget.
Compare health plans
Finding plans in your area…