Medicare Advantage OTC Card Eligible Items and Rules
Maximize your Medicare Advantage OTC card by knowing eligible items and rules. Call (833)-864-8213 for expert plan guidance.
Compare health plans
Finding plans in your area…
Your Medicare Advantage plan may include a benefit that works like a prepaid debit card for everyday health items. This is commonly called an over-the-counter (OTC) card or allowance. It can cover things like pain relievers, vitamins, first aid supplies, and dental hygiene products. But not every item in the aisle qualifies, and the rules vary by plan. Understanding what you can buy, how your allowance is structured, and where you can use the card helps you get the full value from this benefit without surprises at checkout.
This guide breaks down Medicare Advantage OTC card eligible items and rules in plain language. You will learn which product categories typically qualify, what is usually excluded, how monthly and quarterly allowances work, and how to check your balance. You will also see how to compare plans that offer generous OTC benefits during enrollment. If you are reviewing your coverage for the year ahead, Medicare Advantage updates for 2026 can help you spot changes that affect your card and other extra benefits.
What Is a Medicare Advantage OTC Card and How Does It Work?
A Medicare Advantage OTC card is a plan benefit that gives you a set dollar amount to spend on approved health and wellness products. It is not a government-issued benefit. Private insurers offer it as an optional extra, and the specific items, amounts, and rules are set by each plan. The card usually works like a debit card: the plan loads your allowance onto it, and you swipe or enter it at checkout to pay for eligible items. You do not need to submit receipts for reimbursement in most cases, though some plans may require them for online or phone orders.
The allowance is typically separate from your regular plan coverage. It does not affect your premium, deductible, or other cost-sharing. Think of it as a small flexible spending account for health-related purchases. Because it is a plan benefit, you should review your plan's Evidence of Coverage or OTC catalog to confirm exactly what is covered and how the card works. Some plans use a single card for OTC and other benefits, while others issue a separate card.
Most OTC cards are accepted at major retail pharmacies and grocery stores, as well as through the plan's approved online store or catalog. The card may have a network of participating retailers, so it is wise to check before you shop. If you use the card at a store that is not in the network, the purchase may be declined even if the item is normally eligible. The plan's member services team can confirm which stores accept the card and whether online orders are supported.
Typical Medicare Advantage OTC Card Eligible Items
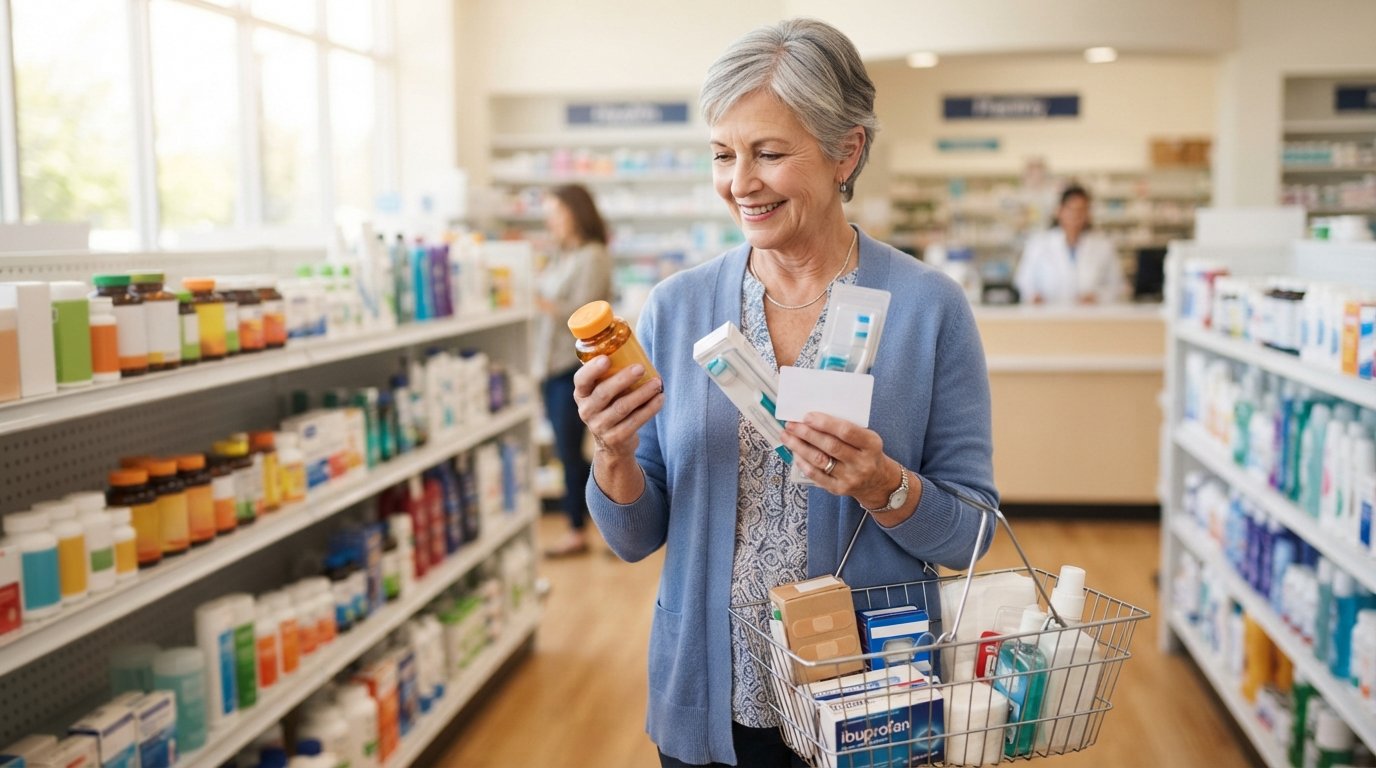
Eligible items generally fall into categories that support everyday health, wellness, and personal care. The exact list is plan-specific, but most Medicare Advantage OTC card eligible items include common over-the-counter products you would find in a pharmacy or the health aisle of a grocery store. The goal is to help you manage minor health needs and maintain good hygiene without paying out of pocket. Below are the categories you are most likely to see.
- Pain relief: Acetaminophen, ibuprofen, aspirin, topical analgesics, and cold or heat packs.
- Vitamins and supplements: Multivitamins, vitamin D, calcium, and certain other supplements when listed in the plan's catalog.
- First aid: Bandages, gauze, antiseptic wipes, medical tape, and instant cold packs.
- Dental hygiene: Toothpaste, toothbrushes, dental floss, and mouthwash.
- Cold, allergy, and sinus products: Decongestants, antihistamines, cough drops, and saline nasal spray.
Some plans also cover items such as reading glasses, compression stockings, heating pads, and incontinence supplies. A few plans include healthy food or produce allowances, but those are usually separate benefits with their own rules. Always check your plan's OTC catalog or formulary list, because a product that is eligible in one plan may be excluded in another. The brand name may also matter: some plans cover generic versions but not brand-name equivalents.
It is also common for plans to update their OTC catalogs each year. An item you bought last year might be removed or added for the new plan year. Reviewing the catalog during the Annual Enrollment Period or when you first receive your card helps you plan your spending. If you are unsure about a specific product, call the member services number on your card or check the plan's website before you buy.
Items That Are Usually Excluded and Why
Medicare Advantage OTC cards are not designed to cover everything you might want to buy at a pharmacy. Plans exclude items that are not considered health-related, that could be covered under another part of Medicare, or that are prohibited by the plan's benefit design. Knowing the common exclusions helps you avoid checkout surprises. The rules are set by the insurer, so always confirm with your plan's catalog, but the following items are typically not eligible.
- Prescription drugs: These are covered under your plan's Part D benefit, not the OTC allowance.
- Cosmetics and beauty products: Makeup, skin creams not classified as medical, and grooming items like razors or shaving cream are usually excluded.
- Food and groceries: Unless your plan offers a separate food benefit, regular groceries and snacks are not covered.
- Alcohol and tobacco: These are never eligible.
- Durable medical equipment: Items like walkers, wheelchairs, and hospital beds go through your plan's DME benefit, not the OTC card.
The reasoning behind these exclusions is straightforward. Medicare Advantage plans must follow Medicare rules about what can be offered as a health benefit. OTC allowances are meant to encourage preventive care and self-management of minor conditions, not to substitute for prescription drug coverage or general household spending. Plans also want to prevent misuse, so they limit the card to products with a clear health purpose. If an item can be purchased with a prescription, it generally belongs under the pharmacy benefit, not the OTC card.
Some items sit in a gray area. For example, a vitamin may be eligible only if it is on the plan's approved list and not marketed for a specific medical condition. A heating pad might be covered, but an electric blanket might not. When in doubt, check the plan's OTC catalog or ask member services. Keeping your receipts can also help if you need to verify a purchase later.
Monthly vs Quarterly Allowances and Rollover Rules
Medicare Advantage OTC allowances come in different structures. The two most common are monthly and quarterly. A monthly allowance gives you a set amount to spend each month, such as $50. A quarterly allowance gives you a larger amount every three months, such as $150. Some plans also offer a single annual allowance. The structure affects how you budget and when you can stock up. Understanding the timing helps you avoid losing unused funds.
Rollover rules vary widely. Some plans allow unused funds to roll over to the next period, up to a certain limit or for the plan year. Others use a "use it or lose it" approach, where any unspent balance expires at the end of the month or quarter. A few plans combine both: you might be able to roll over monthly funds into the next month, but not beyond the quarter. The plan's Evidence of Coverage or OTC card agreement explains the specific rollover policy. If you take expensive items regularly, a plan with rollover can be more valuable because you can save up for larger purchases.
Here is an example. Suppose your plan gives you $40 per month with no rollover. If you spend only $25 in January, the remaining $15 is lost. If the plan allows rollover, that $15 may carry forward, letting you buy a higher-priced item later. Quarterly allowances work similarly: a $120 quarterly allowance with rollover might let you spend $200 in one quarter if you saved from previous quarters. Always check whether the rollover has a cap and whether funds expire at the end of the plan year.
Using Your OTC Card In-Store and Online
Using the card in a store is usually simple. You present the card at checkout along with your items. The cashier swipes it, and the card's system checks whether the items are eligible. If everything qualifies, the purchase goes through. If one item is not eligible, the transaction may be declined entirely or the cashier may need to separate eligible and non-eligible items. Some stores have a dedicated health aisle or a list of approved products, and some plans provide a scanning app that lets you check an item's eligibility before you reach the register.
Online shopping works differently. Many plans have an approved online store or catalog where you can order eligible items using your card. You log in, select products, and enter your card information. The plan's system verifies eligibility automatically. Some plans also allow you to use the card at participating online retailers, but you may need to enter the card like a credit card and the retailer's system must be configured to accept it. If you order by phone, you may need to provide the card number and answer security questions. Keep in mind that shipping and handling fees are usually not covered by the OTC allowance.
Tracking your balance is important, especially if you have a monthly allowance. Most plans offer a member portal or mobile app where you can see your current balance, transaction history, and remaining allowance. You can also call the number on the back of the card. Some cards send text or email alerts when the balance is low. If you share the card with a caregiver, make sure they know the balance and rules so they do not overspend or buy ineligible items. It is a good habit to check your balance before you shop, particularly if you plan to buy several items at once.
Comparing Plans with OTC Benefits During Enrollment
Not all Medicare Advantage plans offer an OTC allowance, and the ones that do vary significantly in generosity. When you compare plans, look beyond the premium and network. The OTC benefit can make a real difference in your out-of-pocket costs for everyday health items. A plan with a slightly higher premium but a generous OTC allowance and rollover may cost you less overall if you regularly buy vitamins, pain relievers, or first aid supplies. During the Annual Enrollment Period, review the plan's OTC catalog and allowance structure alongside other benefits like dental, vision, and hearing.
Start by estimating your monthly spending on eligible items. If you spend $30 a month on vitamins and pain relief, a plan with a $50 monthly allowance and rollover could cover most of that. If you spend less, a smaller allowance may be sufficient. Also consider whether the plan's network includes stores you shop at and whether online ordering is available. A plan with a large allowance but a limited store network may be less convenient. You can use NewMedicare.com's plan comparison tools to see which plans in your area offer OTC benefits and how they stack up.
Another factor is whether the OTC card is combined with other benefits, such as a food allowance or transportation benefit. Some plans bundle these into a single flex card, which can be simpler to use but may have different rules for each category. Read the plan's summary of benefits carefully. If you have questions, a licensed insurance agent can walk you through the details and help you compare options. You can also request a complimentary, no-commitment quote through NewMedicare.com to see plans available in your ZIP code.
Finally, remember that plan benefits can change each year. A plan that offered a $100 quarterly OTC allowance this year might reduce it or change the eligible items next year. Review your Annual Notice of Change, which arrives before the Annual Enrollment Period, to see how your OTC benefit will change. If the changes do not work for you, you can switch plans during enrollment. Comparing plans with an eye on OTC benefits helps you keep more money in your pocket for the health products you use most.
Understanding Medicare Advantage OTC card eligible items and rules puts you in control of a benefit that many members overlook. Check your plan's catalog, track your balance, and plan your purchases around the allowance structure. If you are shopping for coverage, compare OTC benefits alongside premiums, networks, and other extras. And if you need life insurance to protect your family, you can request term life insurance quotes to explore coverage options that fit your budget. With a little planning, your OTC card can be a useful tool for managing everyday health costs.
Compare health plans
Finding plans in your area…