Medicare Advantage for Veterans With VA Coverage
A Medicare Advantage plan for veterans with VA coverage can fill gaps in civilian care. Call 8338648213 for a free plan comparison.
By Alan Prescott
Compare health plans
Finding plans in your area…
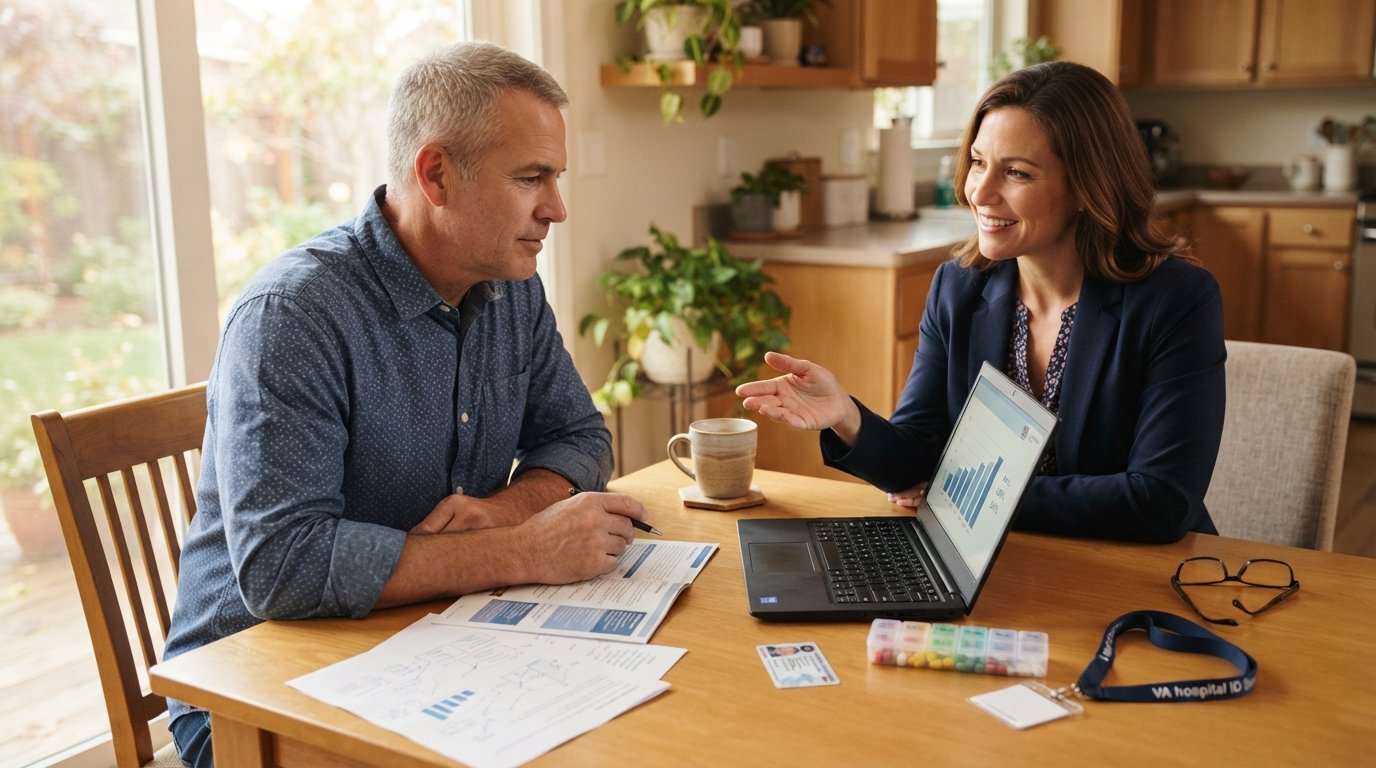
If you are a veteran enrolled in VA health care and you are approaching 65 or already qualify for Medicare, you may be wondering whether a Medicare Advantage plan makes sense alongside your VA benefits. The short answer is that it can, but only if you understand how the two systems interact, when each one pays, and what you give up by enrolling in Medicare Advantage. VA health care and Medicare are separate programs with different rules, and they do not automatically coordinate. That gap creates both opportunities and risks that every veteran should evaluate carefully before signing up.
This guide walks through how a Medicare Advantage plan for veterans with VA coverage actually works in practice, including costs, enrollment timing, prescription drug coverage, and the situations where keeping Original Medicare might serve you better. You will also see how to compare plans without losing the VA benefits you have already earned.
How VA Health Care and Medicare Advantage Fit Together
The Department of Veterans Affairs operates its own health system, and eligibility for VA care is based on service history, disability rating, and other factors. Medicare is a federal health insurance program based primarily on age or disability status. Enrolling in one does not cancel the other, and you can legally hold both at the same time. That said, the two programs do not share a claims system. When you receive care, the provider bills either VA or Medicare, depending on where you go and which benefit you choose to use.
A Medicare Advantage plan is offered by a private insurance company under contract with Medicare. It replaces the way Original Medicare pays for services and typically bundles hospital, medical, and prescription drug coverage into one plan. Some plans also add dental, vision, hearing, and fitness benefits. For veterans, the key question is not whether you can have both, but whether the Advantage plan adds value beyond what VA already provides.
In general, VA health care is strongest when you use VA facilities and approved VA community care. Medicare Advantage is strongest when you want a broader network of civilian doctors and hospitals, predictable copays, and extra benefits such as dental or over-the-counter allowances. Many veterans use VA as their primary source of care and treat Medicare Advantage as a backup for emergencies, travel, or specialist visits outside the VA system.
When a Medicare Advantage Plan Adds Value for Veterans
The value of a Medicare Advantage plan depends heavily on your personal situation. A veteran who lives near a strong VA medical center and uses it for almost everything may find little need for an Advantage plan. A veteran who travels often, lives far from a VA facility, or wants access to local civilian specialists may find that an Advantage plan fills important gaps.
Here are the situations where a Medicare Advantage plan for veterans with VA coverage tends to make the most sense:
- You live more than 30 to 60 minutes from the nearest VA facility and want local care options.
- You travel frequently or spend part of the year in another state where VA care is less convenient.
- You want dental, vision, hearing, or fitness benefits that VA may not fully cover.
- You want an annual out-of-pocket maximum so a major illness does not create unlimited civilian bills.
- You prefer a Medicare Advantage plan that includes prescription drug coverage rather than enrolling in a separate Part D plan.
Each of these situations reflects a real tradeoff. You are not replacing VA care; you are adding a second layer of coverage that can be used when VA care is unavailable, inconvenient, or not the best fit for a particular service. The decision comes down to whether the monthly premium and network restrictions are worth the added flexibility.
Costs: What You Pay With Both VA and Medicare Advantage
One of the most common misunderstandings among veterans is that enrolling in Medicare Advantage will somehow reduce or eliminate VA copays. It will not. VA copays are set by VA rules and are based on your priority group and the type of care you receive. Medicare Advantage copays are set by the private insurer and apply only when you use Medicare-covered services outside the VA system.
That means you could, in theory, pay two sets of cost-sharing depending on where you receive care. In practice, most veterans choose one system as their primary source and use the other as a backup. The table below outlines the general cost structure you should expect.
- VA care: Copays vary by priority group; some veterans pay nothing, others pay modest copays for outpatient visits and prescriptions.
- Medicare Advantage: Monthly premium (often low or $0), plus copays for doctor visits, hospital stays, and prescriptions.
- Part B premium: Required to enroll in Medicare Advantage; most veterans pay the standard Part B premium.
- Out-of-pocket maximum: Medicare Advantage caps annual spending; VA does not have a comparable cap but also does not bill beyond its own copay rules.
Before enrolling, add up the Part B premium, the Advantage plan premium, and the copays you realistically expect to pay. Then compare that total to what you currently spend on VA copays and any private insurance you carry. For many veterans, the math works only if they actually use the civilian network the Advantage plan provides.
Prescription Drugs: VA, Part D, and Medicare Advantage
Prescription coverage is one of the most confusing parts of the VA and Medicare Advantage overlap. VA has its own formulary and its own pharmacy system. Medicare Advantage plans with drug coverage use a different formulary and a different network of pharmacies. You generally cannot use your VA prescription benefit at a Medicare Advantage network pharmacy, and you cannot use your Medicare Advantage drug card at a VA pharmacy.
This means you may have two separate drug benefit systems, each with its own rules. If you fill most prescriptions through VA, you may not need the drug coverage in a Medicare Advantage plan. However, if you also see civilian doctors who prescribe medications not on the VA formulary, the Medicare Advantage drug benefit can be valuable. Some veterans choose a Medicare Advantage plan without drug coverage (a Medicare Advantage-only plan) and rely on VA for prescriptions, while others choose a plan with drug coverage for flexibility.
If you are considering a Medicare Advantage plan with drug coverage, review the formulary carefully. Check whether your current medications are covered, what tier they fall into, and whether prior authorization is required. It is also worth reviewing how Medicare Advantage updates for 2026 may affect formularies, copays, and network rules before you commit to a plan.
Enrollment Timing and Rules for Veterans
Enrollment in Medicare Advantage follows the same rules for veterans as for anyone else. You generally enroll during your Initial Enrollment Period around age 65, or during the Annual Enrollment Period from October 15 to December 7 each year. If you have a qualifying life event, such as moving or losing other coverage, you may qualify for a Special Enrollment Period.
One important point: if you delay enrolling in Medicare because you have VA coverage, you may face late enrollment penalties for Part B and Part D. VA coverage is not considered creditable coverage for Medicare purposes in most cases, so it does not protect you from penalties. If you are 65 or older and eligible for Medicare, it is usually wise to enroll in Part B on time even if you plan to use VA as your primary source of care.
If you are unsure about your enrollment window, a licensed agent can help you map out your options. You can also use InsuranceShopping to compare plan types and understand how Medicare Advantage fits with other coverage you may hold.
Comparing Medicare Advantage Plans as a Veteran
Not all Medicare Advantage plans are the same, and the best plan for a veteran in one state may be a poor fit in another. Plan availability, networks, formularies, and extra benefits vary by county and by insurer. When comparing plans, focus on the factors that matter most for someone with VA coverage.
Start by listing the civilian doctors and hospitals you would want to use if VA care were not available. Then check whether those providers are in the plan network. Next, review the drug formulary if the plan includes prescription coverage. Finally, look at the annual out-of-pocket maximum and the copays for hospital stays, specialist visits, and emergency care.
It also helps to think about how often you actually use VA care. If you use VA for nearly everything, a low-premium Medicare Advantage plan with a broad network may be enough. If you rely on civilian providers for certain specialties, choose a plan that includes those providers and covers the services you need. Take your time, and do not assume that the plan with the lowest premium is the best fit.
Common Mistakes Veterans Make With Medicare Advantage
Many veterans enroll in Medicare Advantage without fully understanding how it interacts with VA benefits. One common mistake is assuming that Medicare Advantage will pay for care that VA would otherwise cover. In reality, the two systems operate independently, and you generally cannot bill both for the same service. Another mistake is dropping VA care entirely after enrolling in Medicare Advantage, only to find that the Advantage plan network does not include the specialists they need.
A third mistake is ignoring prescription drug coverage. If you enroll in a Medicare Advantage plan without drug coverage and later need medications not covered by VA, you could face significant out-of-pocket costs. A fourth mistake is missing enrollment deadlines. Medicare enrollment windows are strict, and missing them can lead to penalties or gaps in coverage.
To avoid these pitfalls, treat Medicare Advantage as a supplement to VA care, not a replacement. Keep your VA enrollment active, use VA for services it handles well, and use Medicare Advantage for the gaps. Review your plan every year during the Annual Enrollment Period, because networks and formularies change regularly.
Frequently Asked Questions
Can I have both VA health care and Medicare Advantage?
Yes. You can be enrolled in VA health care and a Medicare Advantage plan at the same time. The two programs do not cancel each other out, but they also do not coordinate automatically. You choose which benefit to use for each service.
Does Medicare Advantage replace my VA benefits?
No. Medicare Advantage does not replace VA benefits. VA health care remains available to you as long as you remain eligible. Medicare Advantage simply adds another option for receiving care, typically through a private insurer network.
Should I drop VA coverage if I enroll in Medicare Advantage?
Most veterans should not drop VA coverage. VA benefits often include services and prescriptions that Medicare Advantage may not cover, and VA care is generally available at low or no cost depending on your priority group. Keeping both gives you more options.
Do I need to enroll in Part B to get Medicare Advantage?
Yes. To enroll in a Medicare Advantage plan, you must be enrolled in both Medicare Part A and Part B. Most veterans pay the standard Part B premium, although some may qualify for assistance programs.
Can I use my VA pharmacy with a Medicare Advantage plan?
Generally, no. VA pharmacies fill prescriptions under the VA benefit, while Medicare Advantage plans use their own network pharmacies. You will typically need to choose which pharmacy system to use for each prescription.
Making the Decision
Deciding whether to enroll in a Medicare Advantage plan as a veteran with VA coverage is a personal decision that depends on your health needs, where you live, how often you travel, and how much you value flexibility versus low costs. There is no single right answer, but there is a right process: understand how the two systems interact, compare plans carefully, and keep your VA benefits intact.
If you would like help comparing Medicare Advantage plans in your area, a licensed insurance agent can walk you through the options at no cost. You can also request a complimentary quote to see which plans are available where you live. Taking the time to review your choices now can save you money and frustration later.
Compare health plans
Finding plans in your area…