How to Become a Licensed Medicare Agent to Help Family
Want to help a relative with Medicare? Call (833)-864-8213 to speak with a certified agent and learn how to become a licensed Medicare agent to help family.
Compare health plans
Finding plans in your area…
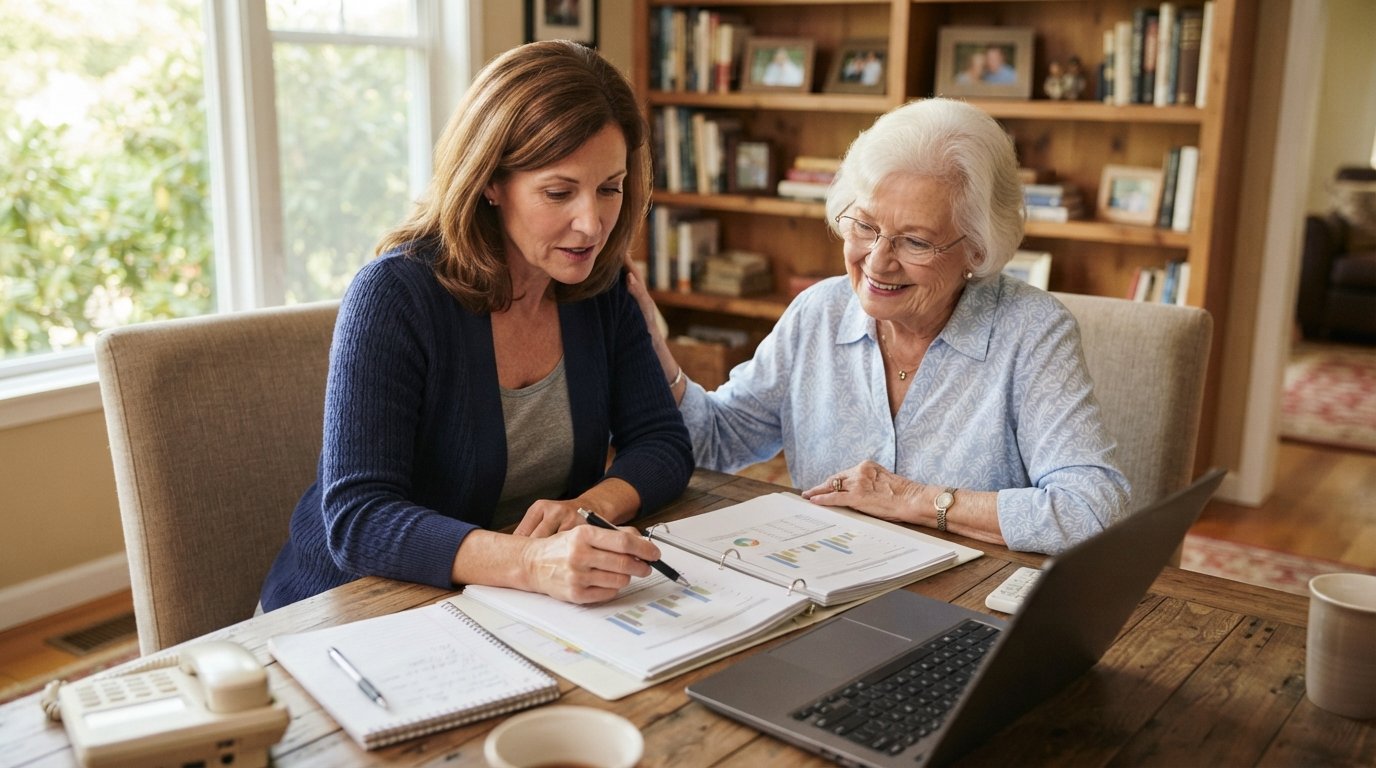
Watching a parent or grandparent struggle with Medicare enrollment can feel frustrating, especially when you want to help but are unsure what you are legally allowed to do. Many family caregivers wonder whether getting a license would let them guide their loved ones through the maze of Part A, Part B, Part D, and Medigap options. The short answer is yes, but the path involves state licensing, federal certification, and a clear understanding of ethical boundaries. This guide walks you through the practical steps, the limits of your authority, and how to connect with professional resources when a family member needs expert help.
Why Family Members Consider Becoming Licensed Medicare Agents
Medicare is not a single plan; it is a collection of federal programs and private insurance products with different rules, costs, and enrollment windows. When a relative is turning 65 or losing employer coverage, the decisions can feel overwhelming. Family members often step in because they want to prevent costly mistakes, such as missing a Part D penalty or choosing a Medigap plan that does not cover a preferred doctor.
Becoming a licensed agent offers a structured way to provide that help. A license demonstrates that you have passed a background check, completed required education, and agreed to comply with state and federal regulations. It also gives you access to carrier-specific training and enrollment platforms that unlicensed individuals cannot use. However, licensing is not a shortcut to giving informal advice; it comes with legal responsibilities and strict rules about what you can and cannot say to a beneficiary.
Before you pursue a license, consider whether your goal is to help one family member or to build a broader practice. If you only need to assist a single relative, you may not need a full license; instead, you can use educational resources and connect with a certified agent who can handle the enrollment. But if you want to be the person who formally presents and enrolls plans, licensing is the right path.
State Licensing and CMS Certification Requirements
Becoming a licensed Medicare agent is a two-layer process: you must satisfy your state's insurance licensing requirements and then obtain federal certification through the Centers for Medicare & Medicaid Services (CMS). Both layers are mandatory for anyone who wants to sell or enroll beneficiaries into Medicare Advantage, Prescription Drug Plans, or Medigap policies.
Step 1: Meet Your State's Insurance Licensing Prerequisites
Each state insurance department sets its own rules, but most require you to be at least 18 years old, complete a pre-licensing education course (typically 20 to 40 hours), pass a licensing exam, and submit fingerprints for a background check. You will also need to apply for a resident insurance producer license and pay the associated fees. Some states offer a combined life and health license, which is useful because Medicare products are health insurance, and Medigap is often regulated alongside life and health lines.
Before you register for a course, check your state's specific requirements. For example, some states require a separate Medicare supplement line of authority, while others include it under the health license. The National Association of Insurance Commissioners (NAIC) provides a state-by-state licensing database, but the most reliable source is your state insurance department's website.
Step 2: Pass the State Exam and Get Fingerprinted
The licensing exam covers insurance principles, state regulations, and Medicare-specific topics such as enrollment periods, guaranteed issue rights, and marketing rules. Many pre-licensing courses include practice exams, and you can usually schedule the real exam through a testing vendor like Pearson VUE or PSI. After you pass, you will submit your application, fingerprints, and fees to the state. Processing times vary from a few days to several weeks.
Step 3: Complete CMS Certification Through a Carrier or Agency
Once you hold a state license, you cannot immediately start enrolling beneficiaries. You must complete the CMS Medicare Compliance and Fraud, Waste, and Abuse (FWA) training, which is typically delivered through America's Health Insurance Plans (AHIP) or a carrier-specific platform. This training covers marketing rules, beneficiary protections, and the consequences of non-compliance. After passing the FWA exam, you must also complete product-specific training for each insurance carrier you represent.
Most new agents obtain CMS certification by contracting with an insurance agency or a carrier directly. The agency provides access to the training portal, assigns you a National Producer Number (NPN), and helps you complete the contracting paperwork. You cannot enroll beneficiaries until all contracting and certification steps are finished and your NPN is active with the carrier.
Here is a summary of the core requirements:
- State insurance producer license with health authority (and Medicare supplement authority where required)
- Passed state licensing exam and background check
- Completed CMS-approved FWA training and passed the exam
- Carrier-specific product training and contracting
- Active National Producer Number (NPN)
Keep in mind that licensing and certification are not one-time events. You must renew your state license every one to two years, complete continuing education credits, and retake the FWA training annually. Carriers may also require periodic recertification.
What a Licensed Agent Can and Cannot Advise On
One of the most important things to understand before you help a family member is the scope of your authority. A licensed Medicare agent can present and enroll beneficiaries into specific insurance products, but cannot provide legal, tax, or medical advice. The line between education and advice is critical, and crossing it can create liability for you and harm for your relative.
As a licensed agent, you are permitted to:
- Explain the differences between Original Medicare, Medicare Advantage, and Medigap
- Compare plan benefits, costs, and networks using carrier-approved materials
- Help a beneficiary complete an enrollment application
- Review prescription drug coverage and check formulary status
- Discuss enrollment periods and potential penalties
You are not permitted to:
- Recommend a specific plan based on a beneficiary's medical needs or financial situation unless you are also a licensed financial advisor or medical professional
- Advise a beneficiary to drop or keep a plan based on personal health information
- Provide tax advice about Medicare premiums or health savings accounts
- Make unsolicited contact with beneficiaries (CMS marketing rules prohibit cold calls and door-to-door solicitation for Medicare Advantage and Part D)
- Enroll a beneficiary without their knowledge or consent, even if you are a family member
These boundaries exist to protect beneficiaries from high-pressure sales tactics and unsuitable recommendations. When you help a family member, you must still follow the same rules as any other agent. That means documenting the conversation, providing required disclosures, and ensuring the beneficiary makes the final decision.
If your relative needs advice that goes beyond plan comparison, such as whether to delay Part B enrollment because they are still working, you should refer them to a qualified professional. In our guide on finding a licensed Medicare agent near you for expert help, we explain how to locate a certified agent who can answer complex questions without a conflict of interest.
Why Educational Resources Are Not the Same as Financial Advice
Many family members start by reading Medicare brochures, watching webinars, or browsing educational websites. These resources are valuable for understanding the basics, but they are not a substitute for personalized advice. Educational content is general in nature; it cannot account for a specific beneficiary's doctors, prescriptions, income, or state-specific rules.
For example, a brochure might explain that Medigap Plan G covers the Part B deductible, but it will not tell you whether Plan G is the best choice for a relative who has a chronic condition and sees specialists frequently. That determination requires a review of the person's healthcare utilization, provider network, and budget. Similarly, an educational article might describe the Part D late enrollment penalty, but it cannot tell you whether a particular beneficiary qualifies for a Special Enrollment Period.
When you become licensed, you gain access to carrier-specific tools and plan comparison platforms that are not available to the general public. These tools let you run drug cost analyses, check provider networks, and estimate out-of-pocket costs. However, even with these tools, you must remember that you are not a financial advisor. If a family member asks whether they should use a health savings account to pay premiums or whether they should invest in a Medigap policy versus a Medicare Advantage plan, you should defer to a licensed financial professional.
The distinction matters because beneficiaries trust family members more than strangers. That trust can lead to undue influence if you are not careful. Always present options neutrally, document the choices, and encourage your relative to ask questions. If you feel pressure to make a decision for them, step back and involve an independent agent or a State Health Insurance Assistance Program (SHIP) counselor.
Ethical Boundaries When Helping a Family Member Enroll
Helping a family member enroll in Medicare is not just a technical process; it is an ethical one. Even with a license, you must navigate family dynamics, potential conflicts of interest, and the risk of unintentional coercion. The following principles can help you stay on the right side of both the law and your family relationships.
First, obtain informed consent. Your relative must understand that you are acting as a licensed agent and that you may receive compensation from an insurance carrier if they enroll in a plan you recommend. CMS requires you to disclose this information, and you should do so in plain language. If your relative is uncomfortable with the arrangement, offer to connect them with an independent agent instead.
Second, avoid pressure. Family relationships carry emotional weight, and a relative may agree to a plan simply to please you. Use a structured enrollment process: present multiple options, give the beneficiary time to review materials, and encourage a second opinion. Never enroll someone on the spot without their explicit permission.
Third, document everything. Keep records of the plans you presented, the questions asked, and the beneficiary's decisions. This protects you if a dispute arises later and demonstrates that you followed CMS marketing rules. Fourth, respect privacy. Medicare beneficiaries have the right to keep their health information confidential. Do not share details with other family members without consent.
Finally, know when to step back. If your relative's situation is complex (for example, they have end-stage renal disease, are dual-eligible for Medicaid, or have employer coverage), you may not have the expertise to help. In those cases, refer them to a certified agent who specializes in complex cases. You can use resources like InsuranceShopping to compare coverage options and connect with licensed professionals who understand the nuances.
How to Connect with a Certified Agent Through NewMedicare
If you decide that becoming licensed is not the right path, or if you want backup support for a family member, NewMedicare.com offers a straightforward way to connect with certified agents. The platform is a privately operated educational resource and service platform that helps individuals understand, compare, and enroll in Medicare plans. It is not affiliated with the U.S. government or CMS, and it provides unbiased information about Parts A, B, C, D, and Medigap.
To get started, you can use the ZIP code-based quote tool on the NewMedicare homepage. After entering basic information, you can request a complimentary, no-commitment quote and speak with a licensed insurance agent who can answer questions about plan availability, costs, and enrollment periods. The service is designed to help beneficiaries and their families make informed decisions without pressure.
NewMedicare also provides educational content on enrollment periods, costs, and plan comparisons. If you are helping a relative who is approaching age 65, you can review the enrollment guidance together and then connect with an agent to finalize the choice. The helpline is available seven days a week, and agents can assist with applications, provider network checks, and prescription drug reviews.
For family members who want to become licensed, NewMedicare's agent resources can be a starting point for understanding the industry. However, the platform does not provide licensing courses; you will need to pursue state licensing and CMS certification through approved providers. Once licensed, you can contract with an agency or carrier to access enrollment tools.
Remember that plan availability varies by state and ZIP code, and NewMedicare represents specific insurance organizations. Always confirm that a plan is available in your relative's area before enrolling. If you are unsure whether a plan covers a particular doctor or drug, ask the agent to verify using carrier tools.
Taking the Next Step
Becoming a licensed Medicare agent to help family is a meaningful way to support loved ones through a confusing process, but it requires a commitment to compliance and ethics. Start by checking your state's licensing requirements, complete the pre-licensing course and exam, and then obtain CMS certification through a carrier or agency. Throughout the process, remember that your role is to educate and facilitate, not to make decisions for your relative.
If you are not ready to pursue a license, you can still help by gathering information, scheduling appointments, and connecting your family member with a certified agent. NewMedicare.com offers a reliable starting point for plan comparisons and agent connections, and the helpline is available to answer questions. Whether you choose to become licensed or to work alongside a professional, the goal is the same: ensuring your family member has the coverage they need at a cost they can afford.
Compare health plans
Finding plans in your area…