Elegibilidad Medicare y Medicaid por Discapacidad: Guia 2026
Elegibilidad Medicare y Medicaid por discapacidad explicada: confirma tu estatus dual y evita costos sorpresa. Llama al 8338648213 para asistencia.
By Rida Zahid
Compare health plans
Finding plans in your area…
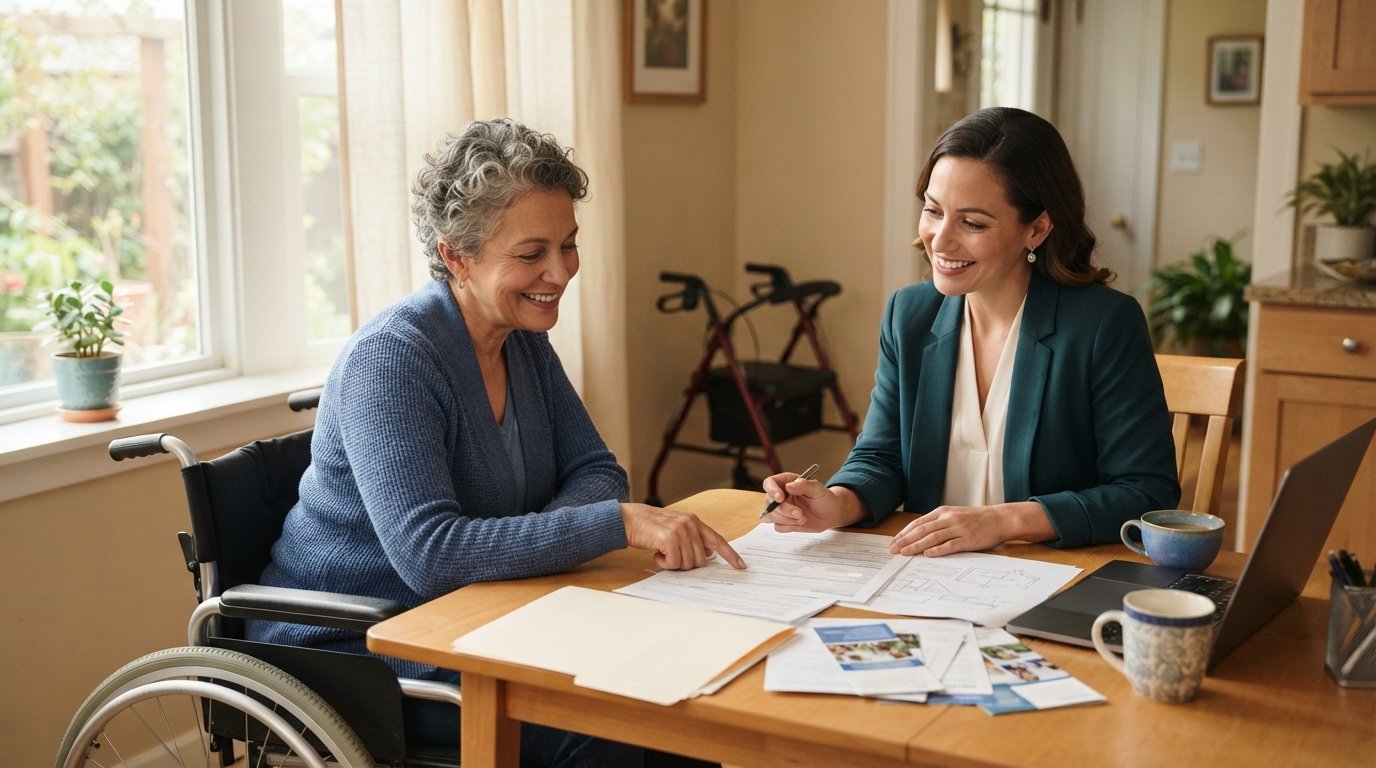
Millions of Americans under age 65 qualify for Medicare and Medicaid because of a disability, yet many never apply because they assume these programs are only for seniors. That assumption can cost you thousands of dollars in uncovered medical bills, prescription costs, and personal care services. If you receive Social Security Disability Insurance (SSDI) benefits, have End-Stage Renal Disease (ESRD), or live with Amyotrophic Lateral Sclerosis (ALS), you may already meet the elegibilidad Medicare y Medicaid por discapacidad requirements, and you may qualify for both programs at the same time.
Understanding how disability-based eligibility works is the first step toward building coverage that actually pays for your care. This guide walks through the 24-month waiting period, the difference between SSDI and SSI, the dual eligible system, income limits, enrollment timelines, and the practical steps you can take to confirm your status and compare plans. Along the way, you will see how a resource like NewMedicare.com can connect you with licensed agents who specialize in disability-related Medicare enrollment.
Who Qualifies for Medicare by Disability Before Age 65
Medicare is best known as health coverage for people 65 and older, but federal law extends eligibility to several groups under 65. The most common pathway is through Social Security Disability Insurance. If you have received SSDI payments for at least 24 months, you are automatically entitled to Medicare Part A and Part B, usually starting the first day of the 25th month of disability benefits. There is no separate application for Medicare in most of these cases; the Social Security Administration notifies you before your coverage begins.
Two other conditions bypass the waiting period entirely. People diagnosed with ALS qualify for Medicare the same month their SSDI benefits begin. People with ESRD who require dialysis or a kidney transplant can enroll in Medicare regardless of age, and they do not need to wait 24 months, though they must meet specific work history or dependent requirements. In both situations, the elegibilidad Medicare y Medicaid por discapacidad rules still apply if you also want Medicaid coverage.
It also helps to know who does not automatically qualify. A diagnosis alone is not enough. You generally need a documented disability that prevents substantial gainful activity, a work history that meets Social Security thresholds, or a qualifying relationship to a worker who has paid Medicare taxes. If you are denied SSDI, you can appeal, and a successful appeal can preserve your original Medicare entitlement date.
Key groups who may qualify for Medicare before 65 include:
- SSDI recipients after 24 months of disability benefits
- People with ALS, who qualify the month SSDI starts
- People with ESRD who need dialysis or a transplant
- Certain dependents or survivors of disabled workers
Once you know which category fits your situation, the next question is whether you also meet Medicaid rules, because Medicaid is where many disability-related costs (like long-term care and transportation) actually get covered.
Medicaid Eligibility for People With Disabilities
Medicaid is a joint federal and state program, which means eligibility rules vary significantly by state. For people with disabilities, there are usually three main pathways: Supplemental Security Income (SSI) enrollment, state disability determinations, and Medicaid buy-in programs for working people with disabilities. In most states, receiving SSI automatically makes you eligible for Medicaid, and the income and asset limits are strict but predictable.
If your income is too high for SSI, you may still qualify through a state disability determination or a Medicaid buy-in program. These programs let you pay a premium or a small share of cost to keep Medicaid while you work. Many states also offer home and community-based services waivers that provide personal care, respite, and supported employment to people who would otherwise need nursing home care.
Income limits are typically expressed as a percentage of the Federal Poverty Level, and they change every year. Asset limits also apply, though some states have eliminated them or raised them substantially. Because these numbers shift annually, checking your state's current thresholds is essential before you apply. Missing a small detail, like an outdated asset figure, can delay coverage for months.
When you combine Medicare and Medicaid eligibility, you become a dual eligible beneficiary, and that status unlocks benefits that neither program provides alone.
Dual Eligible: When Medicare and Medicaid Work Together
Dual eligible beneficiaries are people who qualify for both Medicare and Medicaid. For people with disabilities, this combination is often the most financially protective arrangement available. Medicare becomes the primary payer for doctor visits, hospital stays, and durable medical equipment, while Medicaid fills many of the gaps, including Medicare premiums, deductibles, coinsurance, and services Medicare does not cover, such as long-term personal care.
There are several levels of dual eligibility, and they determine exactly how much help you receive. Full dual eligible beneficiaries receive the most assistance, including payment of Part B premiums and cost sharing. Partial dual eligible beneficiaries may have their premiums covered but still owe some copays. Qualified Medicare Beneficiaries (QMB) get help with premiums and cost sharing, while Specified Low-Income Medicare Beneficiaries (SLMB) get help mainly with Part B premiums.
If you are navigating the dual eligible system for the first time, our guide on Medicare Medicaid enrollment for dual eligible beneficiaries explains how the two programs coordinate and how to avoid coverage gaps. The short version: Medicare pays first, Medicaid pays second, and the combination can reduce your out-of-pocket costs to nearly zero for covered services.
One practical warning: dual eligible status must be maintained. If your income, assets, or living situation changes, report it promptly to your state Medicaid agency. Small changes can move you from full dual to partial dual status, which affects what you pay.
How to Apply and Enroll Step by Step
The enrollment process differs depending on whether you are seeking Medicare, Medicaid, or both. Medicare enrollment for disability is usually automatic once you have received SSDI for 24 months, but you should still verify your start date and confirm that Part B is active. If you have ESRD or ALS, you may need to apply manually through Social Security.
Medicaid enrollment is handled by your state Medicaid office. You can apply online, by phone, or in person, and you will need to provide documentation of your disability, income, assets, and living arrangements. Many states allow you to apply for both Medicare Savings Programs and Medicaid at the same time, which streamlines the process.
A simple sequence that works for most people:
- Confirm your SSDI status and Medicare entitlement date with Social Security.
- Apply for Medicaid through your state agency, even if you think you earn too much.
- Ask about Medicare Savings Programs and dual eligible classifications.
- Compare Medicare Advantage, Medigap, and Part D options once your Medicare is active.
- Review your plans every year during the Annual Enrollment Period.
Once your coverage is active, the next decision is which Medicare plan structure fits your care. That choice has a bigger impact on your budget than most people expect.
Choosing Coverage: Medicare Advantage, Medigap, and Part D
If you have Original Medicare (Parts A and B), you can add a Medigap supplement to cover cost sharing, or you can enroll in a Medicare Advantage plan (Part C) that bundles hospital, medical, and often prescription drug coverage. For people with disabilities, Medicare Advantage plans can be attractive because they frequently include extra benefits like dental, vision, hearing, transportation, and over-the-counter allowances. Medigap plans, by contrast, offer more predictable costs and fewer network restrictions, which can matter if you see specialists regularly.
Prescription drug coverage deserves special attention. Many people with disabilities take multiple medications, and Part D formularies vary widely. A plan that looks cheap on premium can cost far more once you factor in tiers, prior authorizations, and pharmacy networks. If you qualify for Medicaid, you may also qualify for Extra Help (the Low-Income Subsidy), which reduces Part D premiums and copays dramatically.
Because plan availability varies by state and ZIP code, comparing options side by side is the only reliable way to see what you would actually pay. Platforms like NewHealthInsurance help individuals and families compare health coverage options across the country, and NewMedicare.com focuses specifically on Medicare plan comparisons for people with disabilities and other eligible groups. A licensed agent can run your doctors and medications through multiple carriers in a single conversation.
Before you commit to a plan, gather these items:
- A list of your doctors, specialists, and preferred hospitals
- All prescription drugs, dosages, and frequencies
- Your current Medicare and Medicaid status
- Any upcoming procedures or ongoing therapies
With that information, plan comparison becomes a math problem rather than a guess, and you can see whether Medicare Advantage or Medigap plus Part D produces the lower total annual cost for your specific care.
Common Mistakes That Delay Disability Coverage
The most frequent mistake is waiting to apply for Medicaid because of an assumption about income. Many people with disabilities qualify through pathways they have never heard of, including buy-in programs and home and community-based waivers. Applying and being denied is far better than never applying at all, because a denial letter often tells you exactly which program you do qualify for.
Another common error is missing enrollment windows. If you are newly eligible for Medicare due to disability, you have an Initial Enrollment Period, and if you also have employer coverage or Medicaid, different rules may apply. Signing up late can trigger Part B and Part D late enrollment penalties that last as long as you have coverage.
Finally, many beneficiaries never revisit their plan after the first year. Formularies change, networks shrink, and premiums shift annually. A plan that worked well in 2025 may be a poor fit in 2026. Reviewing your coverage every fall, and speaking with a licensed agent when something changes, keeps your costs stable and your care uninterrupted.
Disability-based Medicare and Medicaid eligibility is complicated, but it is not out of reach. Confirm your SSDI or ESRD status, apply for Medicaid even if you are unsure, understand your dual eligible classification, and compare plans with your actual doctors and medications in hand. A few hours of careful review can save you thousands of dollars and protect access to the care you depend on.
Compare health plans
Finding plans in your area…