Does Medicare Cover Long Term Care at Home? 2026 Guide
Does Medicare cover long term care at home? It pays for skilled care only, not custodial help. Learn what is covered and how to fill the gap in 2026.
By Raymond Tolliver
Compare health plans
Finding plans in your area…
Turning 65 or helping a parent age in place often raises one urgent question: does Medicare cover long term care at home? The short answer surprises many families. Original Medicare (Part A and Part B) generally does not pay for the kind of ongoing, day-to-day assistance that most people mean when they say "long term care." That includes help with bathing, dressing, cooking, and supervision for someone with dementia. These are called custodial services, and Medicare was never designed to fund them over the long haul.
However, the picture is more nuanced than a flat "no." Medicare does cover some skilled home health services, and Medicare Advantage plans can add benefits that help with daily living. Understanding where coverage starts and stops can save you from surprise bills and help you plan realistically for the future. This guide breaks down exactly what Medicare pays for at home, what it does not, and how to fill the gaps.
What "Long Term Care at Home" Actually Means
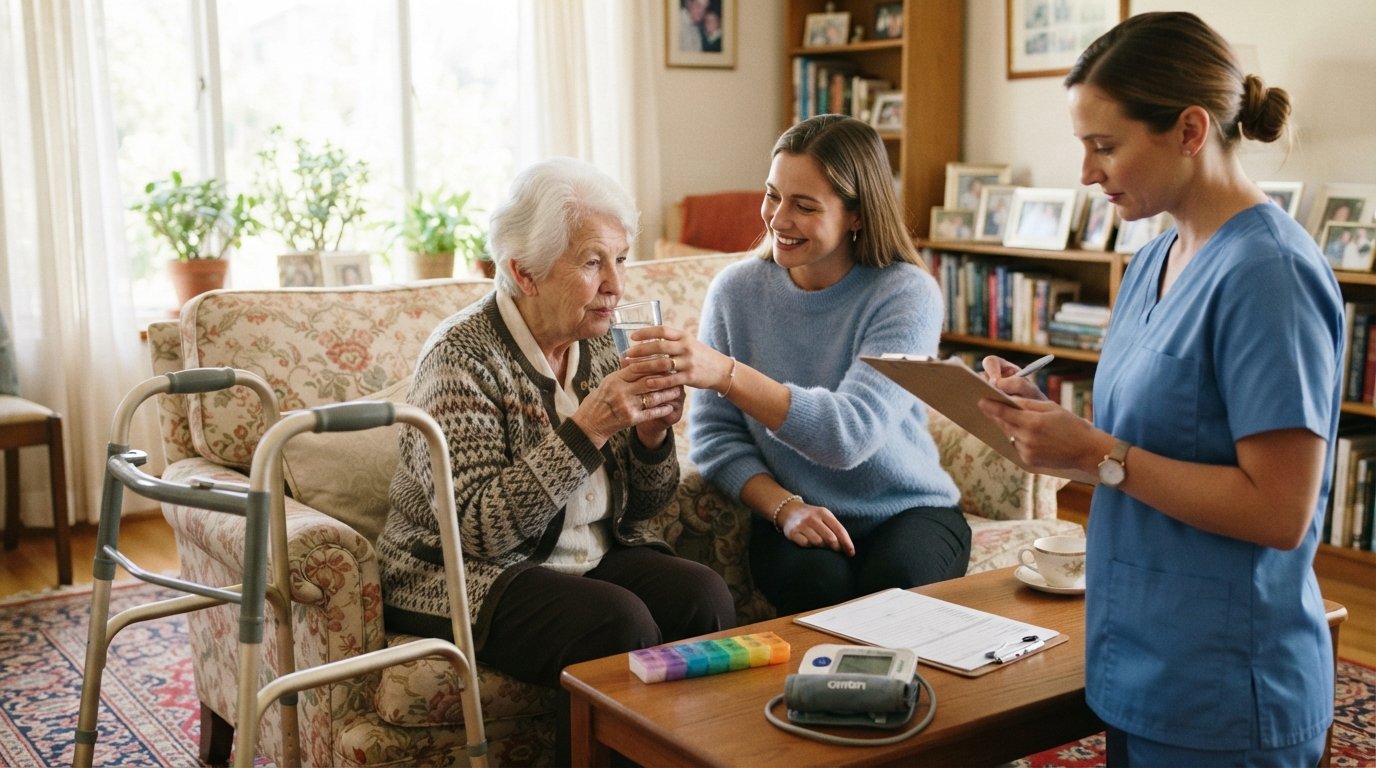
Before you can understand coverage, you need to separate two very different types of care that both happen inside the home. The first is skilled care: medical services ordered by a doctor and delivered by licensed professionals. Examples include wound care after surgery, physical therapy following a hip replacement, or skilled nursing visits to manage a chronic condition. The second is custodial care: non-medical help with the activities of daily living (ADLs) such as bathing, dressing, eating, toileting, and transferring from bed to chair. Custodial care can also include supervision for someone with Alzheimer's disease or another form of dementia.
Medicare's home health benefit is built around skilled care. It pays for intermittent visits from nurses, therapists, and home health aides, but only when a doctor certifies that you need skilled services and you are considered homebound. The moment your need shifts to primarily custodial, Medicare's home health coverage ends. That distinction is the single most important thing to remember when asking whether Medicare covers long term care at home.
It also helps to know who typically needs this care. According to long-term care research, most people who need home-based long term care are older adults managing multiple chronic conditions, people recovering from a serious injury or stroke, and individuals living with progressive cognitive decline. Family members often provide the bulk of this care unpaid, which is why knowing what Medicare will and will not reimburse matters so much.
What Medicare Part A and Part B Cover at Home
Original Medicare does include a home health benefit, and it is more generous than many people realize, as long as you meet the rules. Under Part A and Part B, Medicare covers part-time or intermittent skilled nursing care, physical therapy, occupational therapy, speech-language pathology, medical social services, and home health aide services. It also covers medical supplies and durable medical equipment such as walkers, wheelchairs, and hospital beds when prescribed by a doctor.
To qualify, you must meet several conditions at the same time. A doctor must order the care and create a plan for it. You must need skilled nursing care on an intermittent basis, or physical, occupational, or speech therapy. You must be homebound, meaning leaving home is a considerable and taxing effort. And the home health agency providing your care must be Medicare-certified. If you meet all of these, Medicare generally pays 100 percent of the cost of covered home health services, with no deductible and no coinsurance for the visits themselves. You may still pay 20 percent of the Medicare-approved amount for durable medical equipment.
Here is the catch: coverage is not open-ended. Medicare pays for skilled services only as long as they are medically necessary and your condition is expected to improve or stabilize. Once your doctor determines that you have reached your maximum function or that you no longer need skilled care, the benefit stops. Medicare also does not pay for 24-hour care at home, meal delivery, or homemaker services like cleaning and laundry when they are the only things you need.
What Medicare Does Not Cover: Custodial and Personal Care
This is the part that catches families off guard. Medicare does not cover custodial care, which is the hands-on help with ADLs that most people think of as long term care. If your mother needs someone to help her bathe, dress, and take her medications every day, Medicare will not pay for that aide unless she also qualifies for skilled care under the home health benefit. Even then, the aide visits are limited and tied to the skilled care plan, not to her ongoing personal needs.
Medicare also does not cover adult day care, meal delivery programs, or the cost of assisted living facilities and nursing homes when the stay is primarily for custodial care. It will not pay for a family member to be hired as a paid caregiver. And it does not cover supervision for someone with dementia who is physically healthy but cannot be left alone. These exclusions exist because Medicare is a health insurance program, not a long-term care insurance program.
That leaves families with a significant planning gap. The national average cost of a home health aide runs well into the tens of thousands of dollars per year for full-time care, and costs vary widely by state. Without a plan, those expenses fall on savings, family, or public programs like Medicaid, which has strict income and asset limits. This is why it is so important to know what Medicare covers and to explore supplemental options early, before a crisis hits.
Medicare Advantage Plans and Long Term Care at Home
Medicare Advantage (Part C) plans are an alternative to Original Medicare and often include extra benefits that go beyond what Part A and Part B cover. Many MA plans now offer supplemental benefits such as personal care assistance, adult day care, respite care for family caregivers, and transportation to medical appointments. Some plans even provide in-home support services for members with chronic conditions. These benefits are not guaranteed, and they vary by plan and by county, but they can make a real difference for someone who needs help at home.
It is important to read the plan's Evidence of Coverage carefully. Some plans advertise "in-home support" but limit it to a certain number of hours per year or restrict it to members who meet specific health criteria. Others offer flexible spending cards that can be used for approved home care services. If aging in place is a priority, comparing Medicare Advantage plans side by side is essential. A licensed agent can help you identify which plans in your ZIP code include the home care benefits you need.
Medicare Advantage plans may also cover telehealth visits and remote monitoring, which can reduce the need for in-person care and help you manage chronic conditions from home. These tools are not a substitute for hands-on help, but they can support independence and catch problems early. For 2026, several plans have expanded their supplemental benefits, and staying current on those updates can help you make a smarter choice during enrollment.
Medigap, Medicaid, and Other Ways to Pay for Home Care
If you have Original Medicare, a Medigap (Medicare Supplement) plan can help with some of the costs that Medicare leaves behind, such as copayments and coinsurance. However, Medigap does not add long term care coverage. It only fills gaps in what Original Medicare already covers. So if Medicare does not pay for custodial care, Medigap will not either. That is a common misconception worth clearing up early.
Medicaid is the primary public payer for long term care in the United States, including some home and community-based services. Eligibility is based on income and assets, and rules vary by state. Some states offer waiver programs that allow people to receive care at home instead of in a nursing facility. Applying for Medicaid can be complex, and it is wise to consult a elder law attorney or your state's Medicaid office for guidance.
Other options include long term care insurance, which can be purchased privately and may cover home care, and hybrid life insurance policies with long term care riders. Reverse mortgages and life insurance conversions are sometimes used to free up cash for care. Veterans may qualify for benefits through the VA, including the Aid and Attendance program. Each option has trade-offs, and the best choice depends on your health, finances, and goals.
How to Plan Ahead for Home Care Costs
Planning for long term care at home is not a one-time decision. It is an ongoing process that should start well before you need help. Here are steps you can take to prepare:
- Assess your current and future care needs, including whether you have a family history of conditions that require long term support.
- Review your Medicare coverage and any supplemental plans to understand exactly what is covered at home.
- Compare Medicare Advantage plans in your area that offer supplemental benefits like personal care or respite care.
- Explore long term care insurance or hybrid policies while you are still healthy enough to qualify.
- Consult a financial advisor or elder law attorney to protect assets and understand Medicaid rules in your state.
Taking these steps early gives you more control and more options. It also reduces the burden on family members who might otherwise have to scramble to arrange care during a medical crisis. If you are approaching 65 or already on Medicare, one of the most practical moves is to speak with a licensed insurance agent who can walk you through plan choices and help you understand how each option handles home care.
For a broader look at how Medicare rules and benefits are shifting, including new flexibilities that may affect home-based services, see our guide to Medicare coverage expansion updates for 2026. Staying informed about these changes can help you make decisions that align with your health and financial goals.
If you are also exploring coverage options outside of Medicare, such as for a younger family member or a small business, you can compare affordable health insurance plans at NewHealthInsurance.com to find real-time quotes and state-specific guidance. Having a clear picture of all your insurance options makes it easier to build a plan that protects you and your family.
Key Takeaways on Medicare and Long Term Care at Home
So, does Medicare cover long term care at home? The honest answer is that Medicare covers skilled home health care for a limited time when you meet strict criteria, but it does not cover the custodial care that most people need for an extended period. Medicare Advantage plans may offer supplemental benefits that help with personal care, and Medicaid is the main public safety net for long term care. Private long term care insurance and personal savings fill the remaining gap.
Understanding these distinctions helps you avoid surprises and make informed choices. Whether you are turning 65, caring for a parent, or reviewing your coverage during the Annual Enrollment Period, take the time to compare plans and ask specific questions about home care benefits. A certified agent can provide personalized guidance at no cost and help you find a plan that fits your needs.
Medicare is a powerful program, but it is not designed to pay for everything. By knowing what it covers and planning for what it does not, you can protect your independence and your finances while getting the care you need at home.
Compare health plans
Finding plans in your area…